30초 요약
Matthew Berman reviews 2024 reporting on OpenAI exit agreements, vested equity and restrictions on former employees. Drawing on his startup experience, he questions the fairness of the reported provisions, discusses OpenAI’s denial that it canceled vested equity and notes that he is not a lawyer.
- 1Terms and enforcementThe reported provisions and OpenAI’s statement that it did not claw back vested equity address different questions.
- 2VestingBerman explains how startup equity can vest over time and why it matters to employees.
- 3Signatures and knowledgeVox reported signed documents; Berman cautions that signatures alone do not prove what a person knew about every clause.
- 4Tender offersA warning about access to a private-company sale event differs from cancellation of ownership.
- 5Company responseOpenAI said it was clarifying its position to former employees and releasing non-disparagement obligations.
핵심 정리
- Vox reported exit terms that threatened vested equity or access to company-facilitated liquidity events.
- OpenAI said it had not canceled vested equity and would not do so for refusal to sign departure terms.
- A document’s signature does not by itself establish a signer’s knowledge of every provision.
- Vested equity and participation in a particular tender offer are related but distinct issues.
- The legal effect of any term depends on governing documents and applicable law.
챕터별로 다듬은 전문 읽기
The reported exit terms
Berman introduces Vox’s reporting and OpenAI’s response. He explains vesting and why the provisions mattered.
I examine a 2024 Vox report about OpenAI’s former-employee exit documents and vested equity. I have experience as both a startup founder and employee, but I am not a lawyer. The discussion distinguishes what the documents reportedly said from whether equity was actually canceled and from questions about enforceability.
Vox reported that departing employees faced restrictive exit agreements and potential loss of vested equity if they did not sign. Sam Altman said OpenAI had never clawed back vested equity, apologized for the provision and said it should not have been in the documents. The existence of a provision and whether it was enforced are separate questions.
To explain the stakes, I describe a common startup option arrangement. An option can allow an employee to buy shares at a set price; vesting determines how much of the grant has been earned over time. The value and terms depend on the specific plan and company.
A common schedule is four years with a one-year cliff: after the first year a portion vests, followed by further vesting over time. Employees accept startup risk partly because their equity may become valuable. If the company fails or there is no opportunity to sell, that potential may never become cash.
I have seen confidentiality and non-disparagement agreements offered in exchange for new severance. Linking a new departure agreement to equity already vested strikes me as different and less familiar. I cannot determine the legal effect of any clause without the relevant documents and law.
Documents and leadership knowledge
He discusses Altman’s statement and the signed documents reported by Vox. He distinguishes signing a document from knowledge of every clause.
Altman said OpenAI had not canceled vested equity for refusing a separation or non-disparagement agreement and would not do so. He acknowledged that potential cancellation appeared in prior exit documents and said he had not known about it. I initially thought taking responsibility and correcting the language was the right response.
Vox obtained documents signed by company executives, including an exit letter and equity-holding company documents. The reporting raised questions about leadership’s statement that it had not known of the provisions. A signature on a long document does not, by itself, establish what a signer actually knew about every clause.
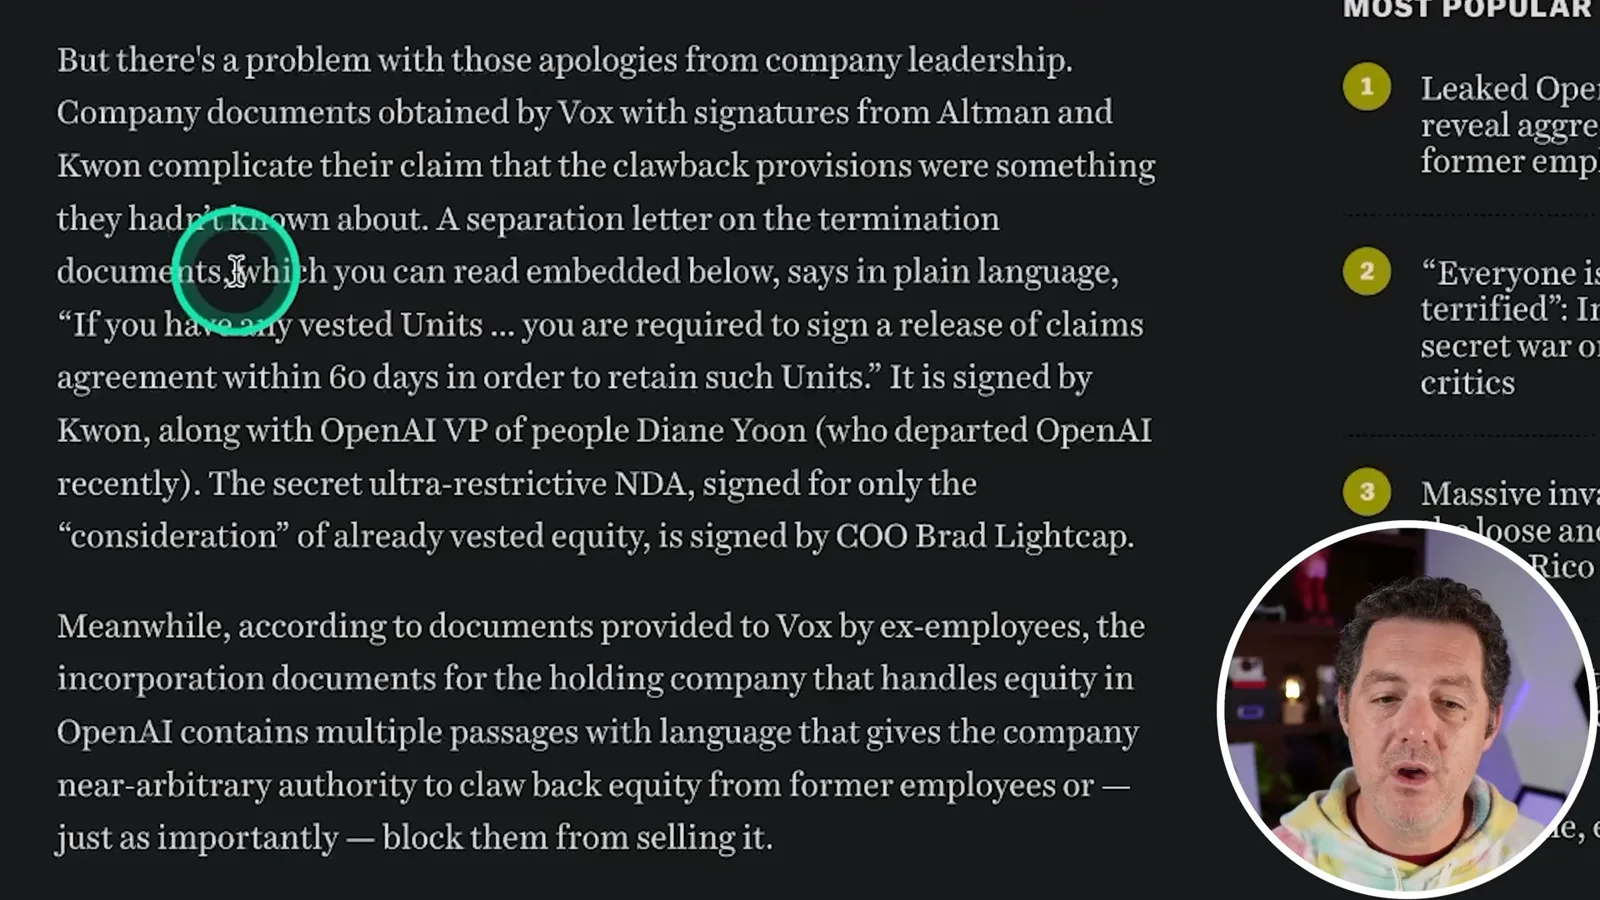
As a founder, I have signed legal documents without understanding every line, and I can imagine that happening elsewhere. That is not an excuse for problematic terms; it is a reason to distinguish the existence and signing of documents from a definitive conclusion about an individual’s knowledge.
Vox reported that the holding-company documents gave OpenAI broad authority regarding equity cancellation or sales, and that an incorporation document bore Altman’s signature. The company told Vox it regretted distress caused and was working to fix the process. I find the lack of a direct answer about knowledge unsatisfying.
Pressure and liquidity
The discussion turns to deadlines, severance, vested equity and tender offers. Legal effects depend on specific documents and law.
The reporting also describes pressure on departing employees and short deadlines. I see a meaningful difference between offering new severance in exchange for a departure agreement and threatening a benefit the employee has already vested. The fairness and legal status of particular terms are distinct questions.
Vox described a former employee who declined to sign and sought counsel. The company subsequently warned about eligibility for company-facilitated tender events. I discuss that as a different issue from cancellation: ownership and access to a particular private-company liquidity event are not identical.
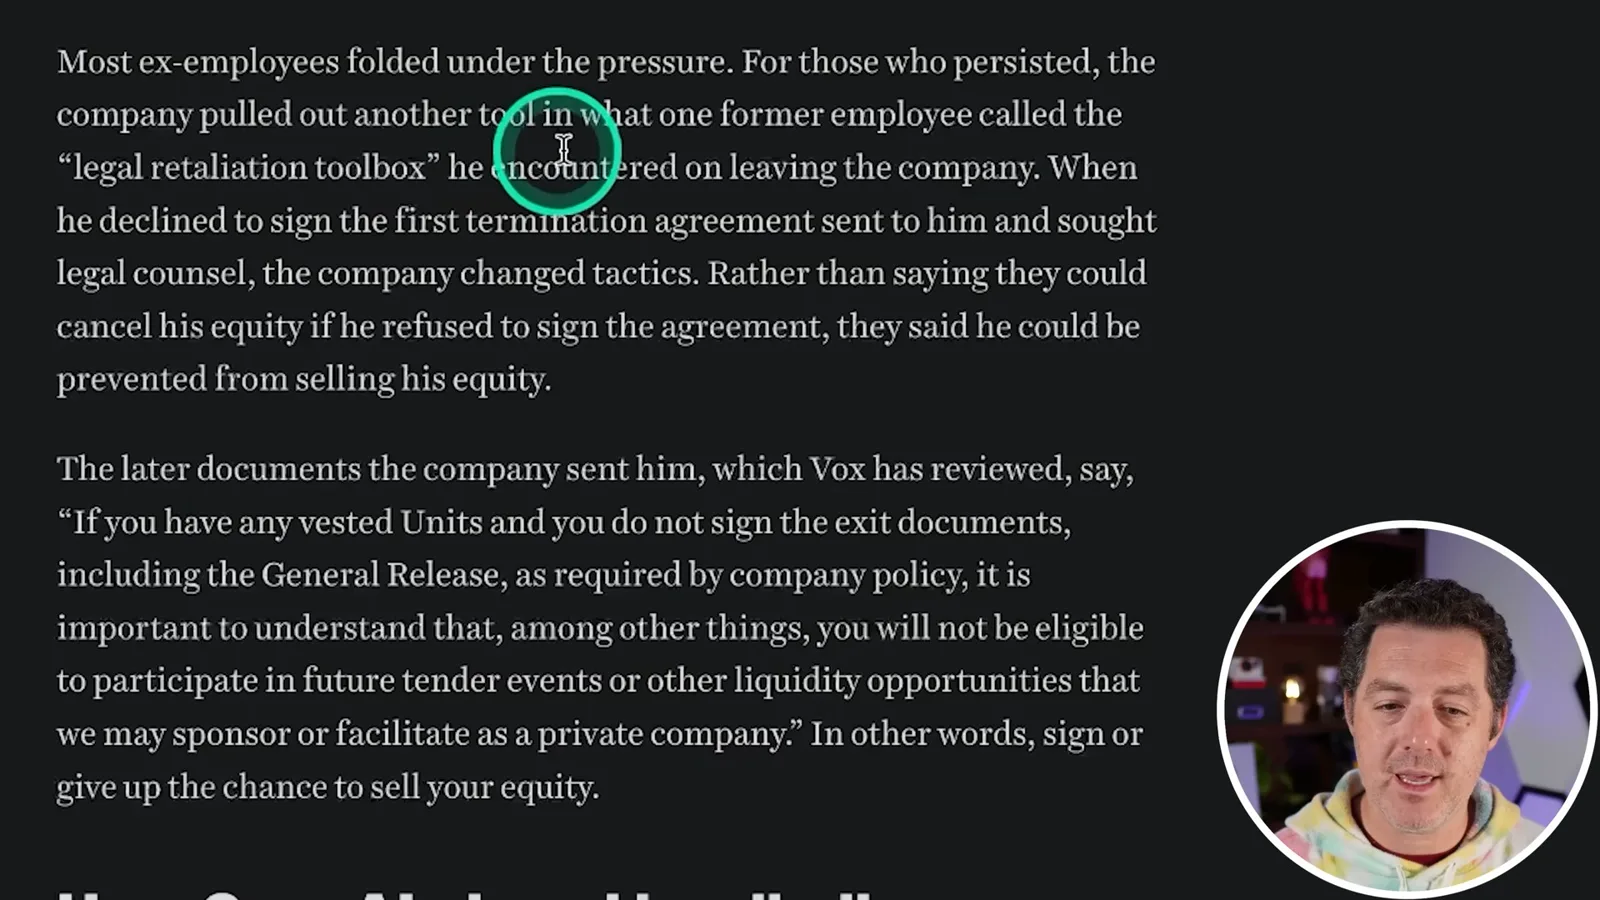
A tender offer can provide an opportunity to sell private-company equity before an IPO or other exit. Eligibility, transfer restrictions and employee rights depend on the governing documents and applicable law. My own comments about what a company can do are opinions, not a legal determination.
Startup employees may wait years for a sale opportunity, and there may never be one. Vox reported clauses concerning forfeiture and discretion over participation in tender offers. I question the fairness and possible enforceability of some provisions, while acknowledging that I do not know the legal answer.
Expectations and response
Berman considers OpenAI’s public commitments and the company’s stated steps to address the issue. He closes with his concerns about pressure on former employees.
I think the controversy drew particular attention because OpenAI had emphasized public benefit, accountability and transparency. Those commitments set expectations about how it treats people and handles disagreement, in addition to the technical performance of its models.
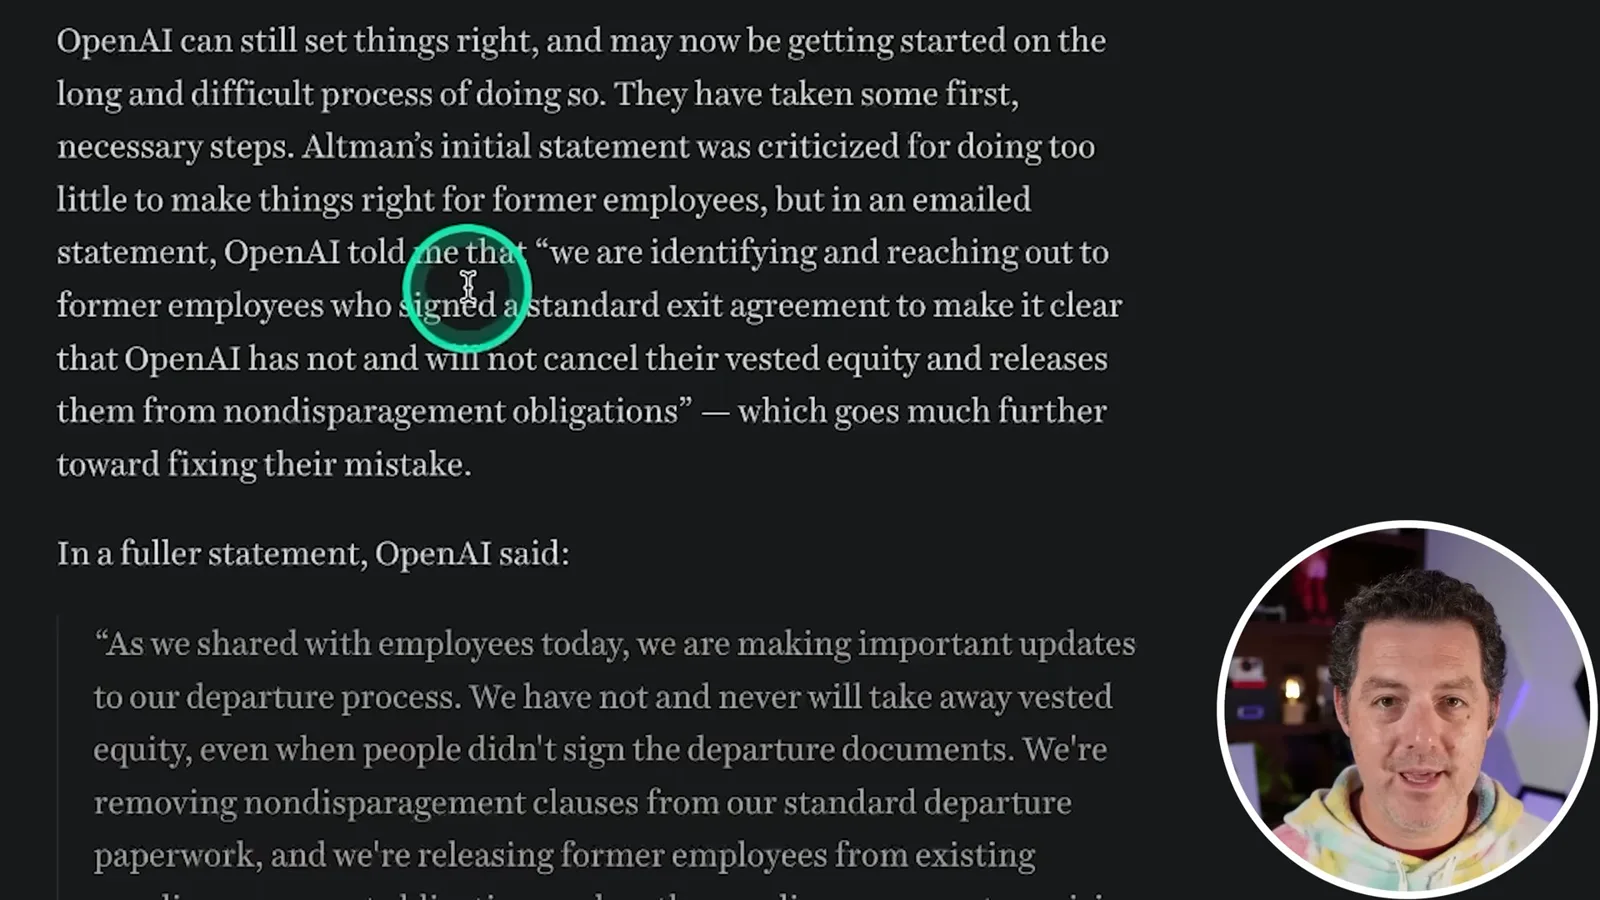
OpenAI told Vox it was reaching out to former employees, clarifying that it had not and would not cancel vested equity, and releasing them from non-disparagement obligations. I welcome correcting the process, while arguing that threatening provisions should not have appeared in the documents in the first place.
The underlying documents are available through the reporting for readers who want to examine them. Whether leaders understood every provision is not established simply by the signatures, and OpenAI said it had not used the clawback. My central concern is the pressure created when already-earned equity is tied to signing additional restrictions.
같은 채널의 다른 글
 25:50EN
 32:20EN
 45:08EN
 0:32EN
 12:14EN
 10:36EN