In 30 Sekunden
Recorded before election results, Jordan Nanos speaks with Maya Barkin, Wayne Ma and Jeremie Eliahou Ontiveros about data center development and state elections. Their forecasts and election scenarios distinguish exposed capacity from projects actually delayed, and examine how developers might address local concerns.
- 12028 is less settledThe team models 62 GW of US additions, mostly not yet under construction.
- 2Pauses versus conditionsA pause can halt approvals; conditions can raise costs while allowing projects to continue.
- 3Exposure is not delayThe 30.3 GW scenario counts planned capacity in exposed states, not predicted delayed capacity.
- 4Grid stabilityA sudden, synchronized drop in data center load can create a grid management problem.
- 5Texas permit riskSome campuses under construction may still need air permits for on-site power.
- 6A broader community approachBarkin recommends transparency, explanation and investments that benefit neighbors.
Das Wichtigste
- SemiAnalysis models approximately 62 GW of US data center additions in 2028, most not yet under construction.
- A permitting pause can stall projects, while conditions can add cost but leave a path to approval.
- The team’s 30.3 GW high-exposure scenario is not a forecast of capacity that will necessarily be delayed.
- Texas air permits and on-site power are a potential downside risk even for some 2027 projects.
- Developers face bipartisan pressure over grid costs, water, tax incentives and local benefits.
Den bearbeiteten Text nach Kapiteln lesen
The 2027 and 2028 pipelines
The panel explains why construction already underway offers 2027 more protection than the 2028 pipeline.
Jordan Nanos introduces a discussion of US data center moratoriums and the midterm elections, recorded on Election Day before the results. Maya Barkin, Wayne Ma and Jeremie Eliahou Ontiveros join him to explain how state and local politics could affect the next wave of construction.
Barkin says SemiAnalysis regards the 2027 pipeline as largely locked in: roughly three quarters of the capacity in the top 20 states is already under construction. The team therefore remains comfortable with its forecast of more than 50 GW of global additions in 2027, though permits and power still matter.
The bigger uncertainty is 2028. The firm’s model projects about 62 GW of US additions, most not yet under construction and concentrated in states electing governors. Projects still need permits, electricity and construction schedules while state policies may be rewritten.
Barkin says the key question is whether projects can meet stricter terms, not simply which party wins. Texas had already stopped issuing certain environmental permits while ERCOT audited interconnection requests; with Texas representing nearly 30% of projected US additions in 2028, a delay there could shift the national forecast.
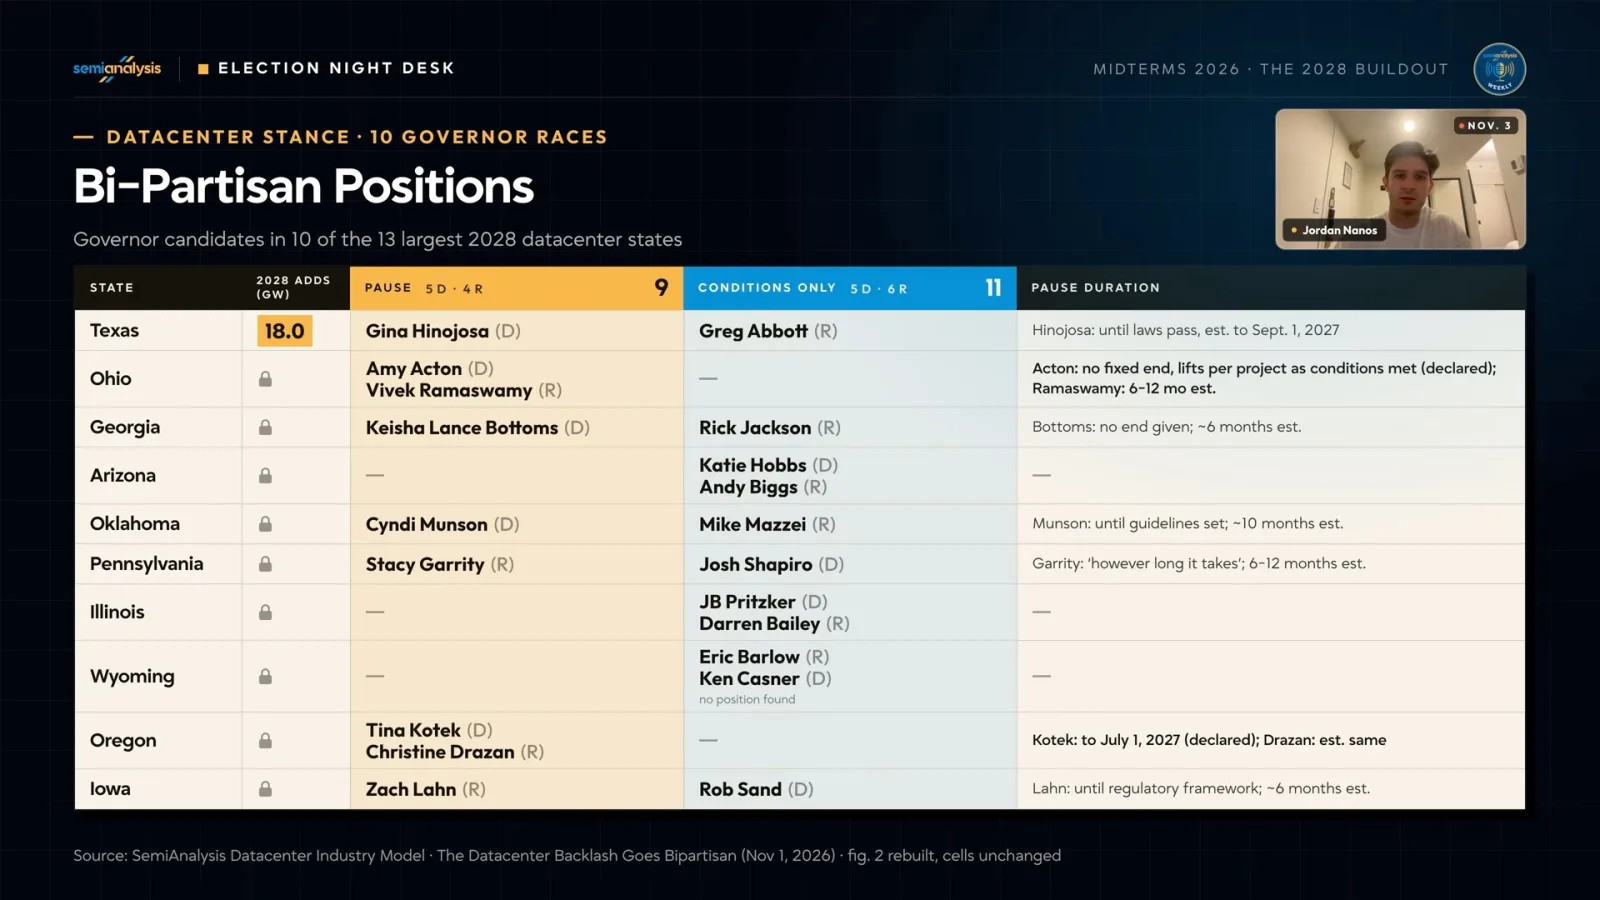
In September, SemiAnalysis estimated that only about 1.5 GW of roughly 20 GW exposed to local restrictions was actually delayed. Since then, Barkin says the Texas permit freeze has made on-site power less certain as an escape route. In ten gubernatorial races, the team counted nine nominees favoring a pause and eleven favoring conditions.
Pauses and conditions
Barkin distinguishes permit moratoriums from tighter requirements and presents election scenarios.
Barkin distinguishes a pause from conditions. A moratorium can stop the processing or issuance of a building, air or zoning permit. Conditions may make a project slower or more expensive, but developers can still move forward by funding grid upgrades, changing cooling designs or negotiating community agreements.
Some requirements were already emerging: water-use studies, credits to households for infrastructure costs, and more transparency as companies such as AWS and Google move away from nondisclosure agreements. A pause is different because a project without its permits may be unable to proceed at all.
The team modeled election scenarios rather than predicting the exact amount of lost capacity. Barkin says a sweep by candidates favoring moratoriums would expose 30.3 GW of planned 2028 capacity. Exposure means projects in affected states, not a forecast that all 30.3 GW will be delayed.
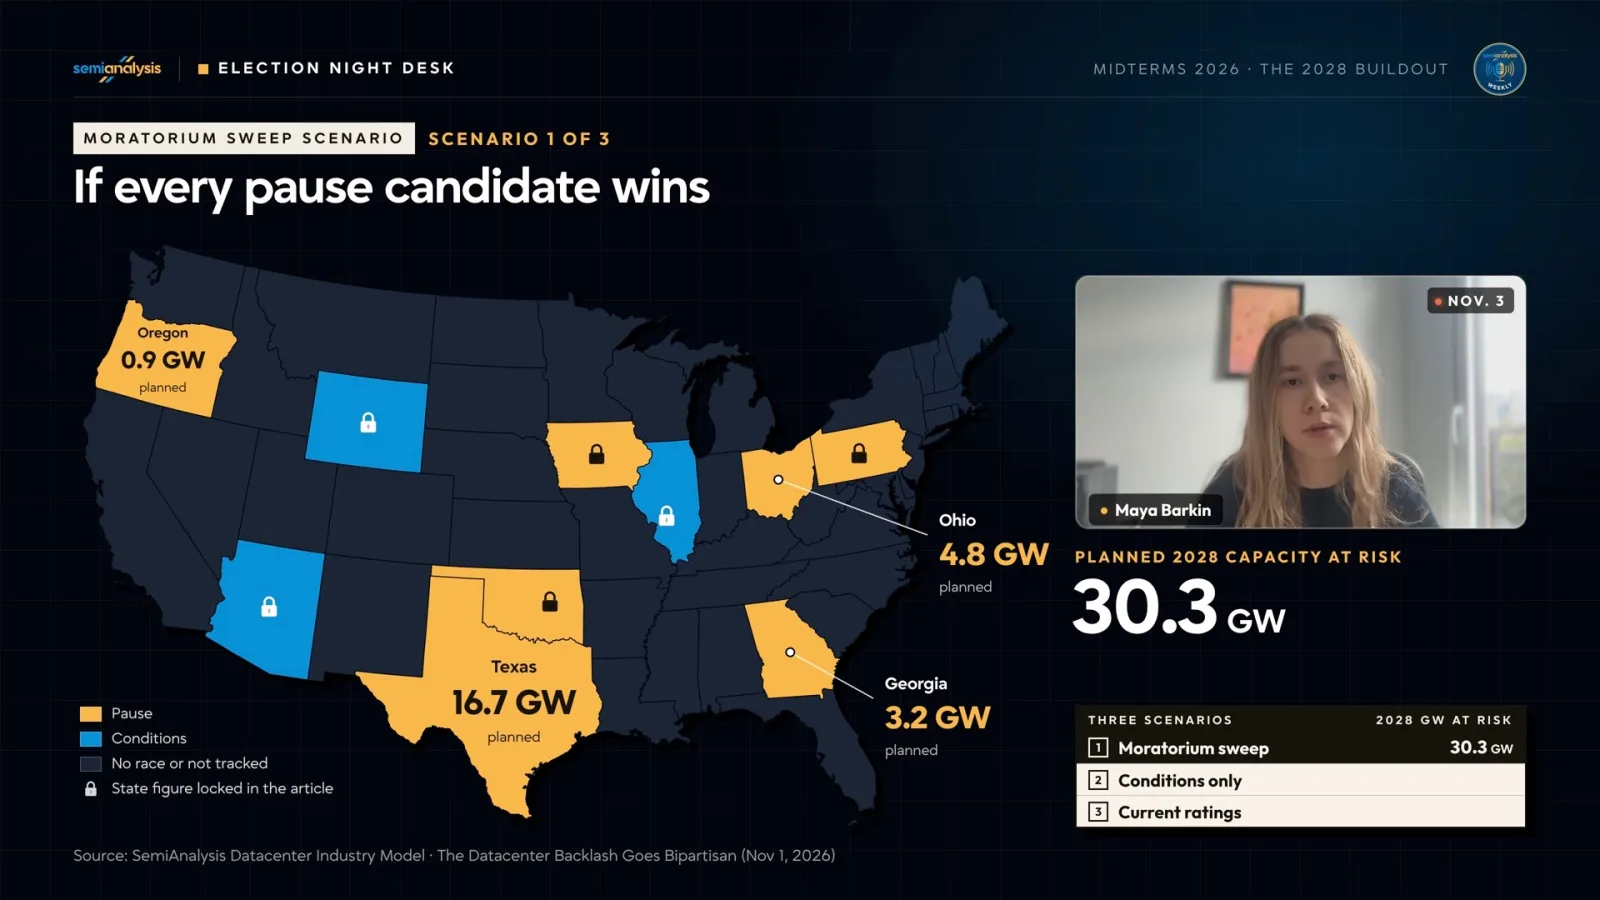
A conditions-only outcome and the team’s then-current polling scenario each put the exposed figure at 5.7 GW, Barkin says. The panel stresses that these are scenario inputs based on campaign positions, not a guarantee of what governors or legislatures will ultimately do.
A bipartisan backlash
The participants discuss scale, local concerns, grid risk and changing incentives.
Ma says the backlash crosses party lines. Residents near proposed projects may worry about AI’s impact on jobs, water, electricity and household costs; candidates from both parties have responded. States that once competed to attract data centers through incentives are reconsidering those terms.
Ontiveros says the change follows a dramatic shift in scale. Data centers once combined high project value with a relatively small industrial footprint. As campuses multiply and grow, however, noise, water demand and the cumulative effects of many projects have become harder for communities to ignore.
He argues that the balance of bargaining power has shifted too. More valuable facilities and constrained access to power give communities an opportunity to seek a larger contribution or offer fewer tax breaks. In his view, developers can absorb more local costs as a small share of total project value.
Grid stability presents a separate technical issue. Ontiveros describes an event in Virginia in which a voltage dip prompted data centers to transfer to backup systems and abruptly drop roughly 1.5 GW of load. He says synchronized load loss at that scale can threaten grid stability.
Ontiveros expects developers to adapt with equipment that makes facilities better grid participants and with more water-efficient cooling. He sees the pushback as partly justified: a design that worked when only a few facilities were built may need to change when many large projects arrive at once.
Ma points to Ohio, where he says the annual cost of data center incentives rose far beyond earlier expectations, reaching $1.6 billion in the latest year he cites. That scale helps explain why candidates from both parties are discussing the rollback of incentives.
Ontiveros adds that tax advantages for large industrial projects are not inherently unusual. The issue, he says, is that strong demand now gives jurisdictions room to negotiate greater contributions from developers, and some companies are already accepting fewer breaks or investing more locally.
State and local decisions
Governors, legislatures and local authorities each influence approval and project economics.
Nanos asks how a governor’s race translates into decisions on individual sites. Barkin says local approvals remain project-specific and responsive to neighbors. Governors can act quickly by directing agencies, whereas legislatures set laws and tax rules through a slower process.
Before the election, Barkin considered a reelection scenario for Texas Governor Greg Abbott and expected existing restrictions might eventually ease. She notes that some directives would expire without being actively reversed, potentially allowing permitting to resume around December or early the following year. This was a pre-election assessment, not an election result.
Nanos lists the policy levers beyond a simple pause: grid costs and ratepayer protections, tax incentives, water reporting and limits, on-site power, community benefits, nondisclosure agreements and local control. Barkin says support for tougher conditions cuts across the political spectrum.
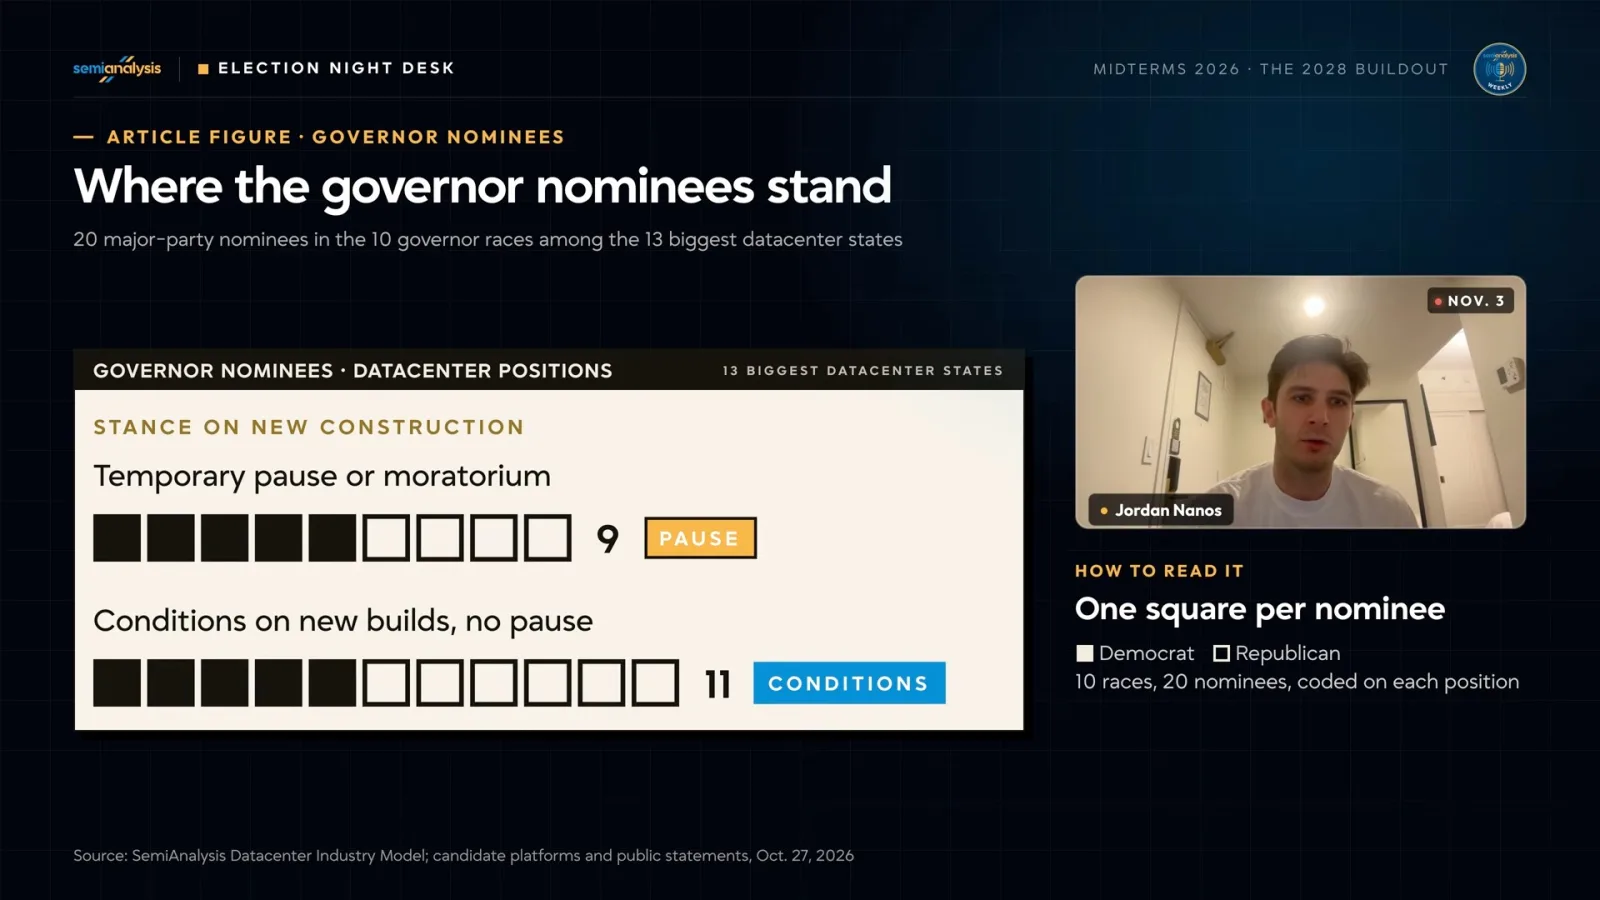
Ma sees differences in emphasis: Democrats in the races studied were more likely to discuss union labor and ending NDAs, while Republicans more often emphasized local control. He nevertheless finds broad alignment around household costs, power and incentives; individual candidate positions vary.
Texas and 2027 risks
Air permits for on-site power could affect some already-funded campuses in Texas.
Ontiveros says the 2027 forecast is based heavily on projects whose shells are already under construction and that generally have construction and other permits. To disrupt that year’s buildout, a policy must affect something those projects still need. The team regards Texas air permits as one possible vulnerability.
Some funded Texas campuses were being built without their final air permits, he says. If a pause continued into mid-2027, a developer might finish much of a building but be unable to construct its on-site power plant. He calls that a possible downside scenario, not the team’s base case.
Barkin compares the competing Texas proposals as they stood before the vote. Under an Abbott scenario, an ERCOT audit targeted for early December could be followed by stricter permitting; she says many projects could absorb that interruption in their schedules.
She describes the alternative proposal as a longer pause until protections on household costs and other issues passed the legislature. Depending on when new rules took effect, the team estimated an additional five to nine months relative to a December restart, leaving less schedule flexibility for 2027 projects.
Georgia and federal policy
The panel considers uncertain candidate positions, local grids and federal cost allocation.
Nanos cautions that campaign statements are not the same as implemented policy. Barkin agrees that their analysis takes candidates’ propositions at face value. The discussion then turns to Georgia, where the participants describe a close contest and note that some important candidate positions had not been stated.
Ontiveros argues that statewide rules also need to account for local power systems. A blanket requirement to bring one’s own power might be less sensible where grid capacity is available than where a project is off-grid. Different grids within a state can operate under different rules.
At the federal level, Barkin expects a change in congressional control to have limited immediate effects given presidential veto power and the need for votes in the Senate. She sees bipartisan support for making large electricity users bear their own grid costs, potentially through upfront payments or collateral.
Working with communities
Transparency, local jobs and infrastructure are discussed as potential responses to opposition.
The panel discusses the political response to constituent concerns. Barkin says the firm is researching the backlash further. The participants also argue that industry communication has lagged and that fear about AI and employment can shape how residents view nearby projects.
Ma suggests that dropping NDAs could reduce the perception of secrecy. He points to potential community benefits such as public facilities and infrastructure, particularly in economically underdeveloped areas. He also believes companies need to explain their energy and water practices more clearly.
Barkin says uncertainty about jobs and the future can make a new data center feel unwelcome even when developers emphasize the technology’s benefits. An official she interviewed joked that residents might feel differently if developers were known for hanging Christmas lights.
Nanos describes visiting a construction site and meeting workers who valued the pay and travel opportunities. He acknowledges that this sample was biased toward people already working there and that a multibillion-dollar project is not necessarily the most efficient way to create a given number of jobs.
Asked whether financial payments alone could change opinion, Ma says people the team spoke to wanted more than a payoff. Barkin adds that some construction workers are specialists brought from outside the area, so promised jobs do not automatically translate into local employment.
Nanos raises the possibility of training local workers and questions whether data center demand is a short-lived surge or a longer-term shift. He suggests that reducing tax incentives could leave more public revenue locally when developers are already eager to build.
Barkin favors a broader approach: transparent discussions, fewer NDAs, clear explanations of water and environmental practices, and visible community contributions such as schools or roads. She says such measures can help, while distinguishing community investment from simply paying individuals to stop objecting.
As the discussion ends, the panel says it is watching Texas and Georgia most closely. Texas matters because of its large share of planned capacity; Georgia stood out as a close race at the time of recording. The team’s scenarios remain contingent on actual decisions after the election.
Mehr aus diesem Kanal
 51:52EN
 SemiAnalysis· 3. Nov. 2026Podcast · 3 StimmenHow GDPx Tests Frontier AI: Inside SemiAnalysis’s New BenchmarkGast: Max Kan, Andrew Megalaa · Moderation: Jordan NanosThe team behind GDPx explains task quality, domain selection, grading and the trade-off between public scrutiny and private evaluations.
 55:06ENSemiAnalysis· 27. Okt. 2026Podcast · 4 StimmenAnthropic's S-1: Revenue, Compute Costs and the Race to ScaleThe SemiAnalysis panel examines Anthropic’s filing, from improving compute economics to customer concentration and competition.
 34:35ENSemiAnalysis· 23. Okt. 2026Podcast · 3 StimmenSemiAnalysis on ASML's Hybrid-Bonding Patents, HBM Economics and the Next Tool EcosystemGast: Sherry Zhang, Howie · Moderation: Jordan NanosJordan Nanos, Sherry Zhang and Howie examine a track-based bonding design that brings the wafer to the die, then explain why adoption depends on precision, cleanliness, economics and a changing supply chain.
 34:47ENSemiAnalysis· 20. Okt. 2026Podcast · 3 StimmenWhy SemiAnalysis Raised Its 2027 Data Center ForecastGast: Jeremie Ontiveros, Reyk Knuhtsen · Moderation: Jordan NanosJeremie Ontiveros and Reyk Knuhtsen explain their project-level model, construction risks and the possibility of a future capacity imbalance.
 44:12ENSemiAnalysis· 14. Okt. 2026Podcast · 3 StimmenGLM 5.3, Sparse Attention and the Cost of InferenceGast: Kimbo Chen, Wenyao Gao · Moderation: Jordan NanosSemiAnalysis examines memory bottlenecks, AMD and NVIDIA serving results, post-training and support for Chinese chips.
 1:23:18ENSemiAnalysis· 9. Okt. 2026Podcast · 2 StimmenWho Will Finance the AI Infrastructure Build-Out?Gast: Daniel Nishball · Moderation: Jordan NanosSemiAnalysis examines projected capital needs, GPU rental economics and the guarantees supporting data center financing.