30초 요약
ChatGPT Finances product lead Ethan Bloch shows Peter Yang how he uses financial context to investigate charges, prepare tax questions, compare investment costs, review card rewards and model major decisions. The demonstration uses a fictional person and some synthetic data. Estimates, privacy descriptions and feature availability reflect the interview; financial decisions require verification of current rules and individual circumstances. The episode is sponsored by Wispr Flow, with Riverside and Linear also listed.
- 1Review recurring chargesAsk for potential duplicates, price changes and fees, then check the underlying transactions; one apparent duplicate in the demo had an explanation.
- 2Understand the data boundaryBloch distinguishes raw financial data from information brought into chats; verify current disclosures and settings before connecting accounts.
- 3Prepare questions for a tax professionalUse a checklist and document gathering to investigate possible savings, but verify eligibility and calculations.
- 4Compare fund costs carefullyLook beyond expense ratios to holdings, taxes, transaction costs and suitability before changing investments.
- 5Model major decisionsInteractive time-off and housing scenarios reveal how results change with assumptions; they do not predict the future.
- 6Set recurring checks deliberatelySubscription, spending and cash reviews can surface questions, subject to available features and permissions.
핵심 정리
- A transaction review can identify possible duplicates or subscriptions to investigate; repeated charges are not automatically errors.
- Bloch describes the bank connection as read-only and distinguishes raw account data from information in chats; check current settings and disclosures.
- Tax and investment suggestions require verification of eligibility, assumptions, fees and potential consequences.
- Interactive models for time off or housing are scenarios driven by assumptions, not forecasts or recommendations.
- Recurring checks can surface questions about spending and idle cash, subject to permissions and product limits.
챕터별로 다듬은 전문 읽기
Background and the first spending review
Bloch introduces his finance work and a fictional subscription audit.
Ethan Bloch, product lead for ChatGPT Finances, joins Peter Yang to demonstrate ways to examine spending and model financial decisions. The walkthrough uses a fictional character, Jim, and some synthetic data. Wispr Flow sponsors the episode; Riverside and Linear are also listed as sponsors.
Bloch describes a long interest in personal finance, including losing his early trading gains during the internet downturn. He founded Digit to help people save and says the limitations of earlier technology shaped his interest in using current models with financial data.
His first prompt asks the assistant to review 90 days of transactions for subscriptions, price increases, duplicate charges, fees and unusually high bills. The fictional demonstration flags several candidates. A repeated salon charge turns out to have an explanation, illustrating why a flagged transaction still needs verification.
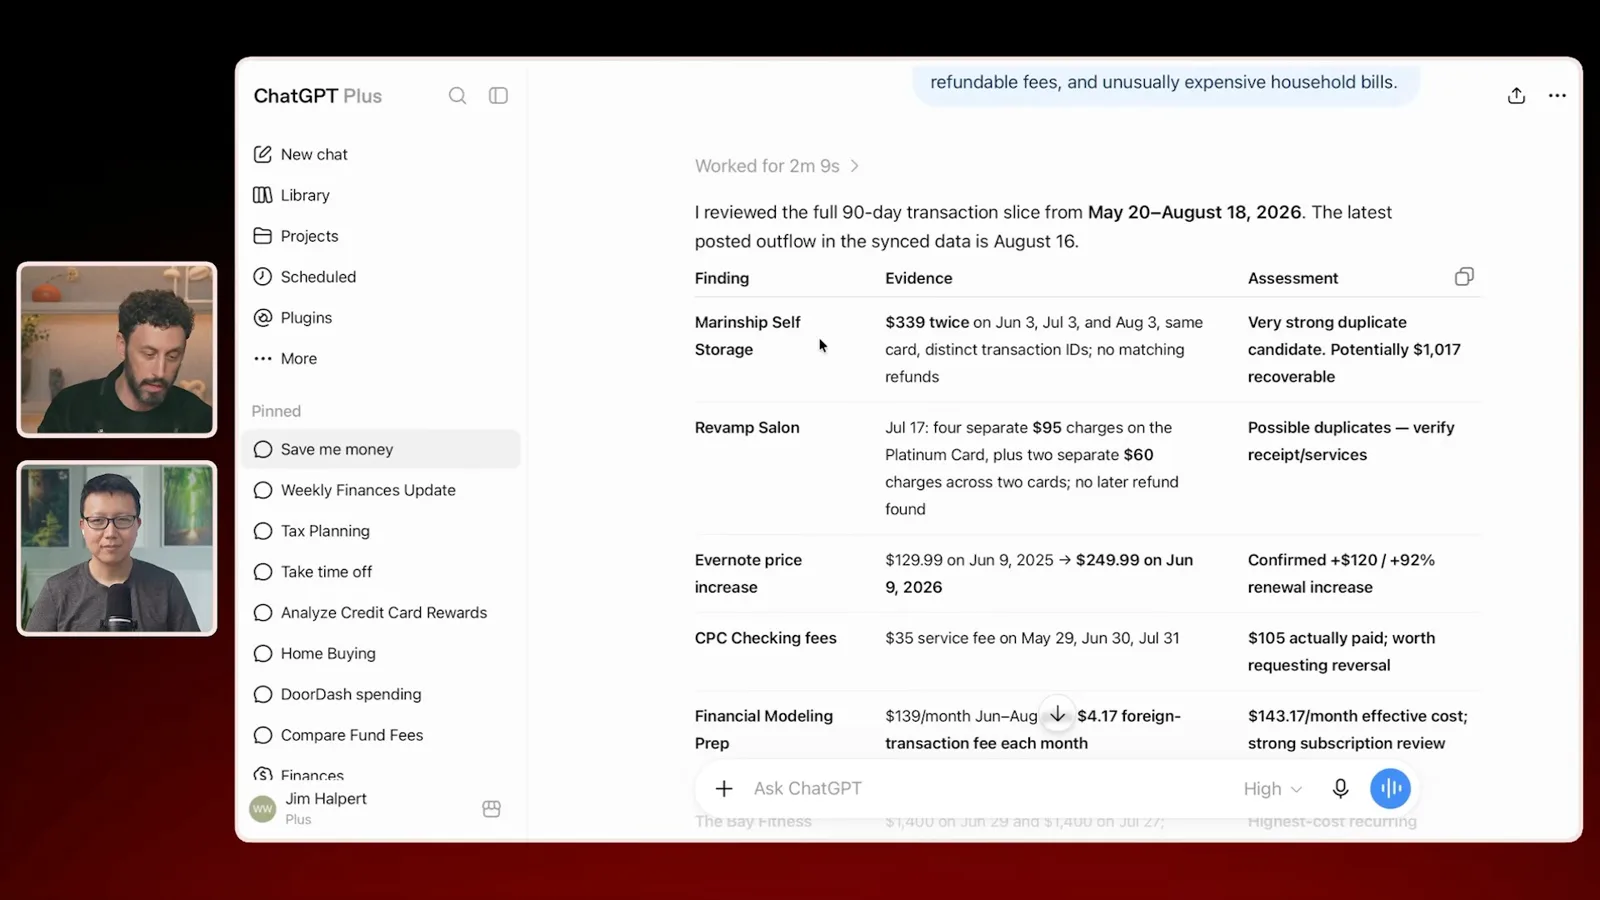
Bloch describes drafting a message to resolve a suspected duplicate storage charge and recounts a separate personal hotel reimbursement. Yang shares a similar customer-service example. These are anecdotes, not guaranteed savings; communications and financial actions depend on the user’s permissions and review.
Connections, privacy and the dashboard
The speakers discuss account access, categorization and data settings.
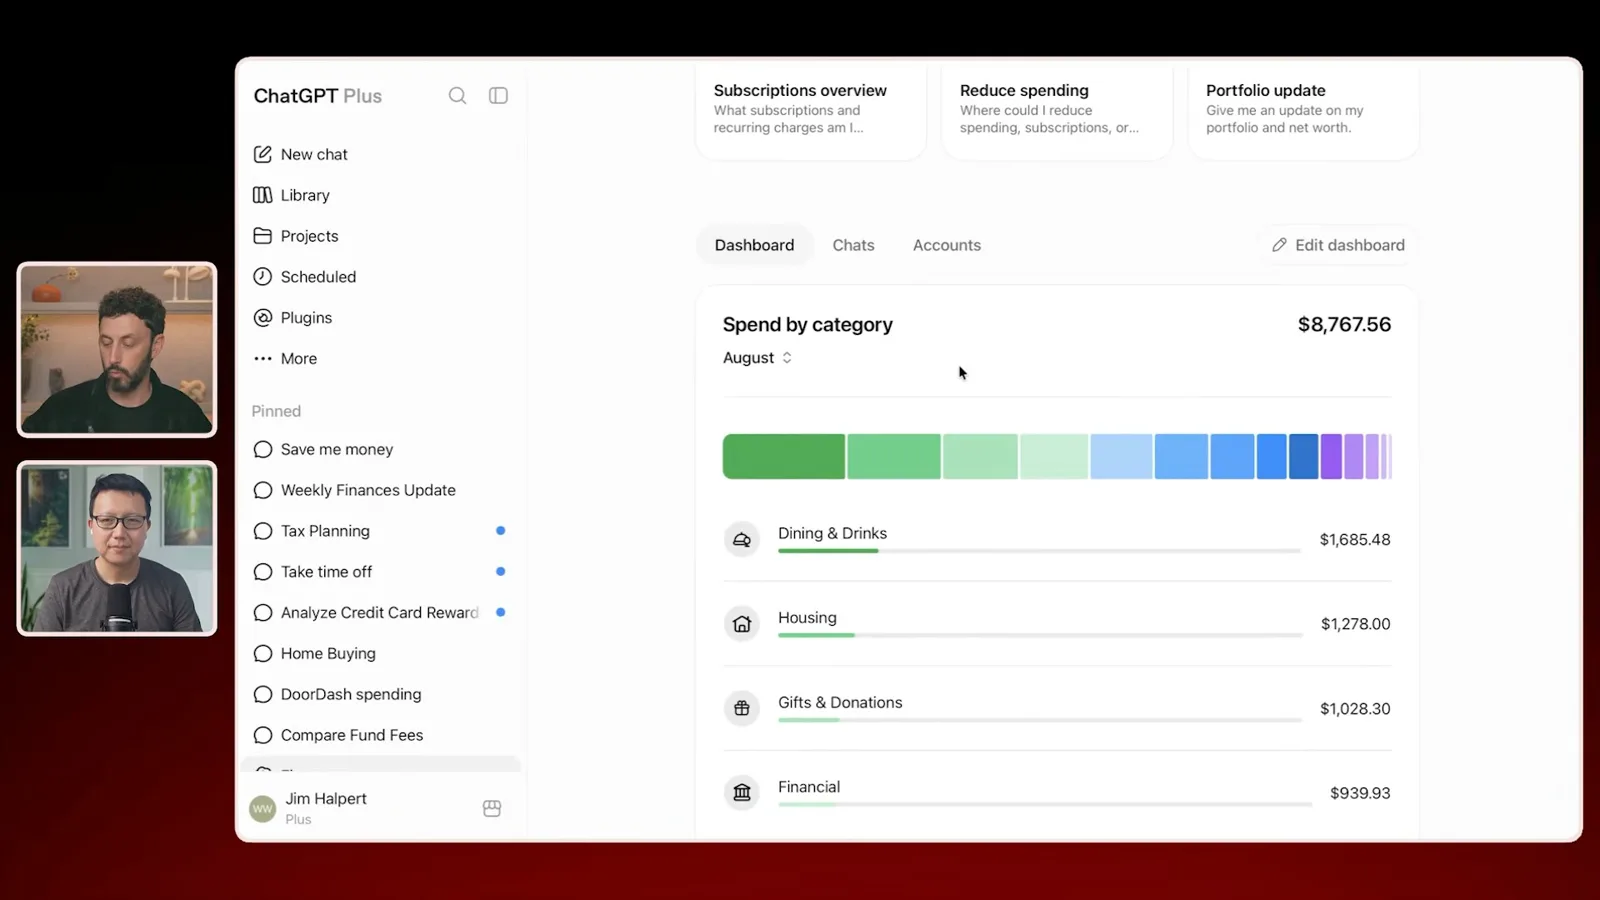
Bloch demonstrates the account connection and dashboard. He says the bank connection uses Plaid and describes the connection in the video as read-only. The dashboard groups spending, shows balances and investment information, and lets users correct categories; the speakers acknowledge that automated categorization can be wrong.
On privacy, Bloch says raw balances and transactions are not used for training, while information brought into a chat may be treated differently depending on settings. This is his explanation at the time of the interview; users should check current product disclosures and settings before connecting sensitive accounts.
Updates and spending alerts
Weekly summaries and spending thresholds make monitoring more proactive.
Bloch describes an automatically created weekly update and optional notifications for spending thresholds. In his fictional DoorDash example, the assistant tracks monthly spending against a chosen amount. He says users can turn off the weekly update and create other scheduled checks, subject to plan limits.
Taxes, investment costs and card rewards
Bloch demonstrates research workflows for three different financial questions.
For taxes, he asks for possible savings based on the available context, then requests an estimate, a visual summary and a to-do list. He describes using the assistant to gather documents and prepare responses for his accountant. Suggested tax savings are estimates, and eligibility, current law and individual circumstances need checking with a qualified professional.
For investment accounts, Bloch suggests asking for a comparison of fund expenses and possible alternatives. A lower expense ratio alone does not establish equivalence or make a switch appropriate: holdings, taxes, trading costs and account rules also matter. His example is a starting point for research.
For credit cards, he asks the assistant to compare spending categories and card benefits. A visualization shows a hypothetical reward cap and possible changes. Rewards, caps, annual fees and eligibility depend on the actual card terms, and the illustrative estimate is not a promised gain.
Modeling time off and home buying
Interactive scenarios help a fictional household compare assumptions.
For time off, Bloch uses a fictional family scenario and asks for an interactive model with several paths. Sliders change the length of the break and spending assumptions so the couple can discuss their cash reserve. The display is only as reliable as its inputs and calculations.
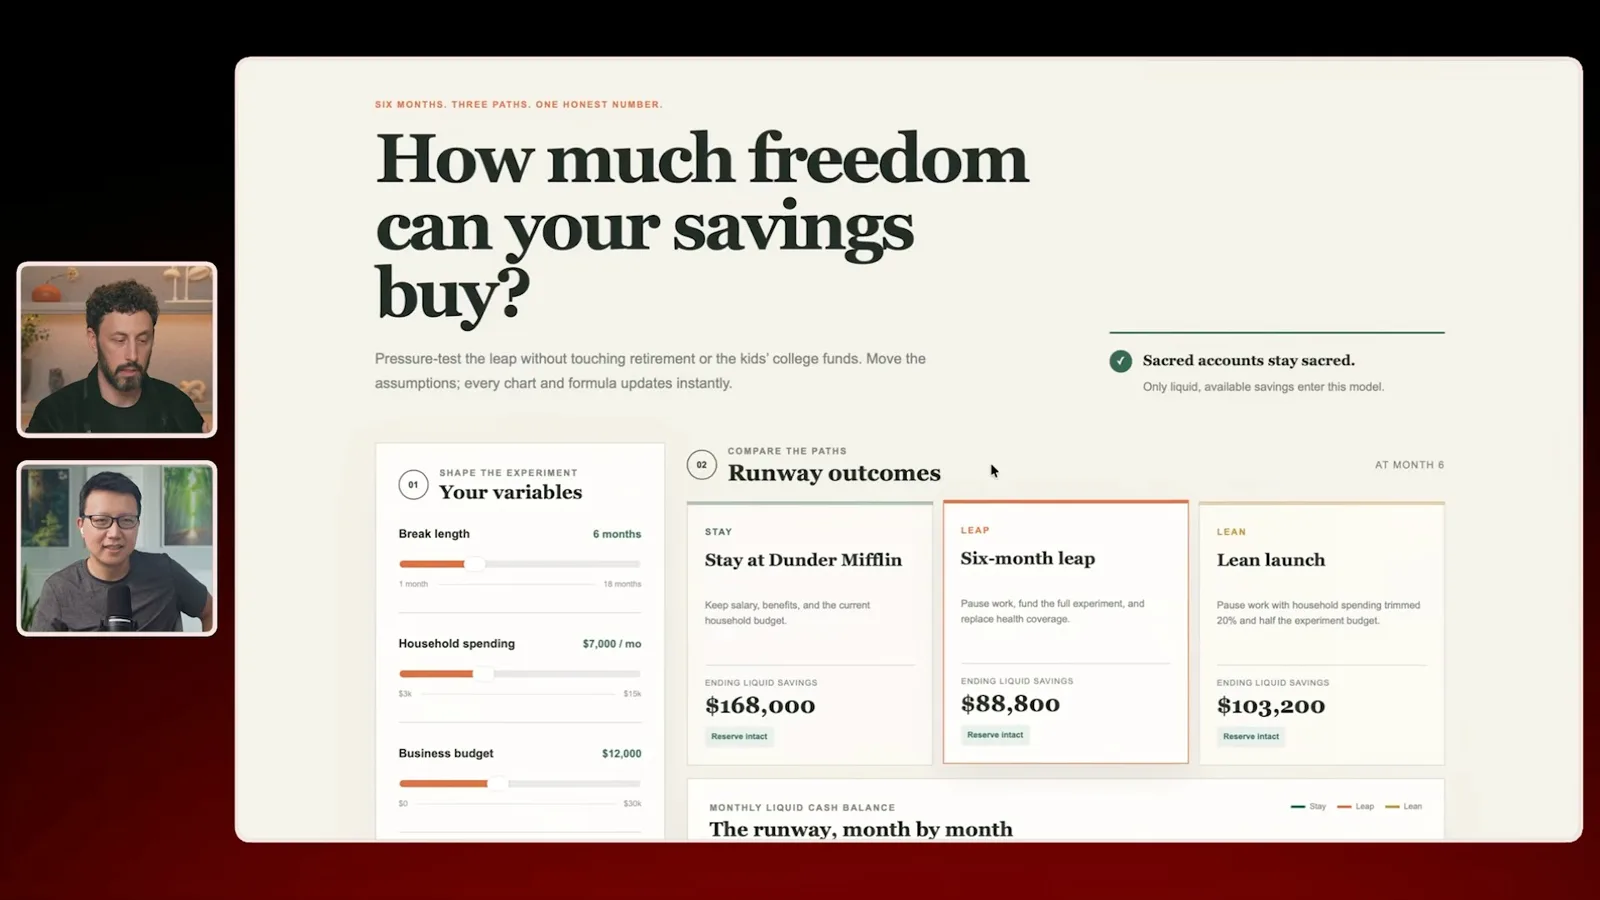
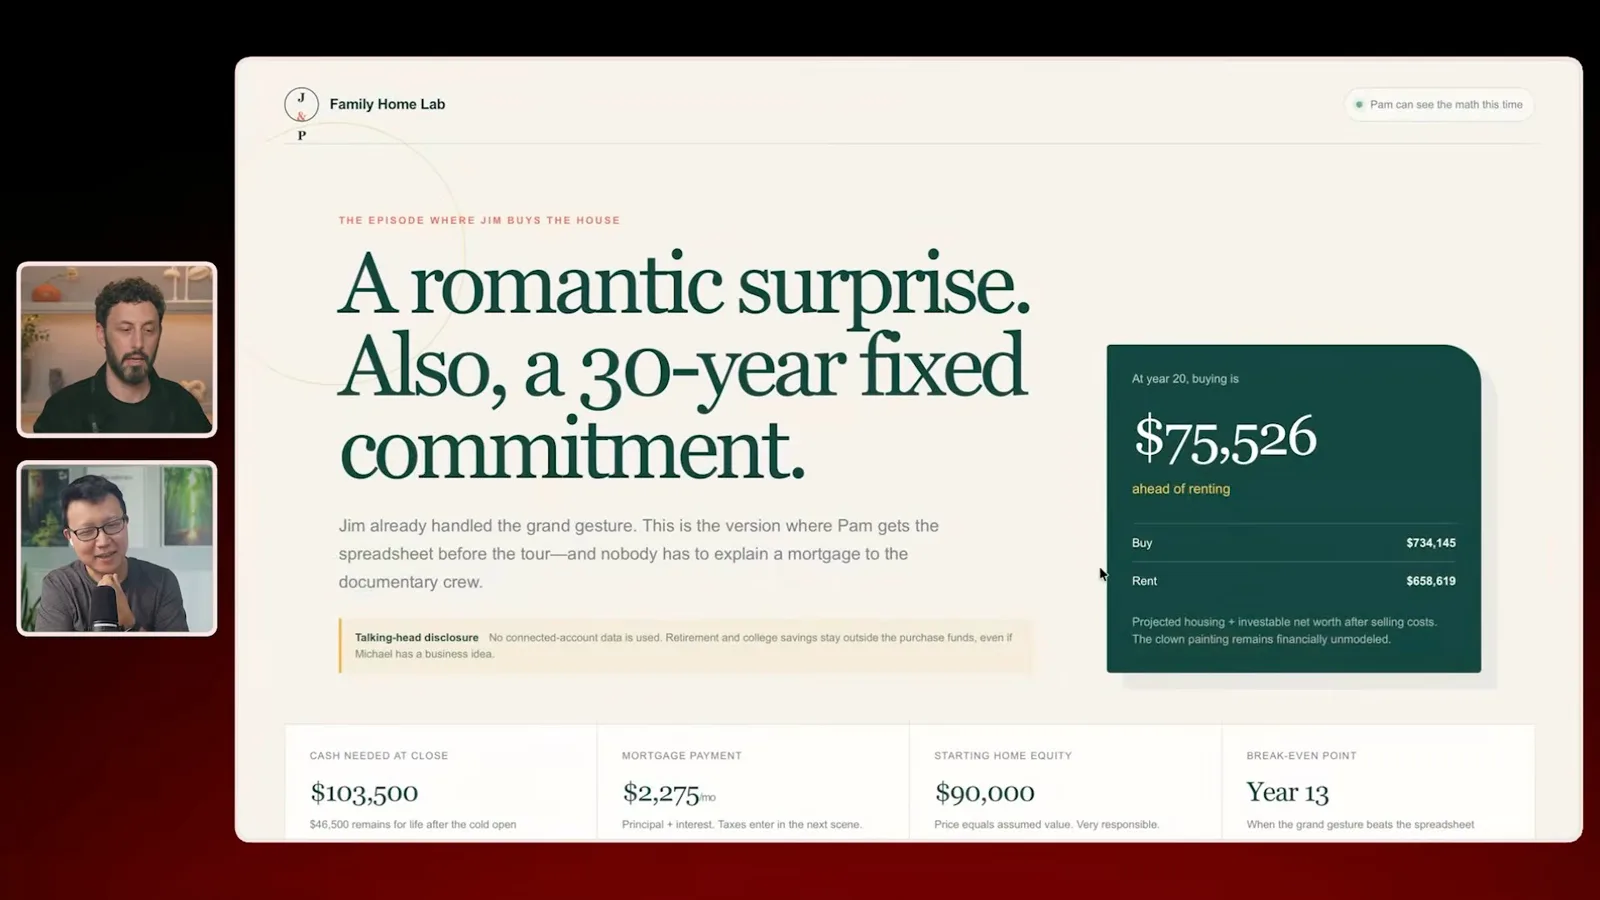
The speakers also discuss retirement and a rent-versus-buy model. Bloch says a person can supply figures manually rather than connecting every account. The purchase model compares outcomes under adjustable assumptions; its numbers are illustrative, not a recommendation to buy or rent.
Recurring checks and building the product
Bloch discusses scheduled reviews, team workflows and product priorities.
Bloch describes recurring checks for subscriptions, family spending and idle cash. He says bank connections are read-only and browser-based actions at financial institutions may be blocked or vary by provider. He treats these routines as prompts for review, not a guarantee of savings or execution.
On the product team, Bloch says the group ships frequent small changes while applying testing and care to sensitive data. He describes a workflow in which engineers and designers use agents to build prototypes, then review those prototypes together rather than relying on lengthy specifications for every feature.
Asked about the future, Bloch says he has no specific announcement and wants to make the existing product easier to discover and use. The discussion closes with the potential for financial tools and voice interactions, framed as a product direction rather than a promised feature.
같은 채널의 다른 글
 46:40EN
 Peter Yang· 2026년 11월 8일팟캐스트 · 2명Ashley Alexander: How AI Helps Me Care for My Parents With Cancer게스트 Ashley Alexander · 진행자 Peter YangA caregiver uses AI to prepare for appointments, organize records and ask better questions—while keeping doctors at the center of treatment.
 17:50ENPeter Yang· 2026년 11월 4일팟캐스트Peter Yang’s Five Steps for Using AI to Help Care for His MotherYang uses a shared care brief and organized records to navigate appointments, while making time for family.
 15:03ENPeter Yang· 2026년 11월 3일팟캐스트How Peter Yang Used an AI Phone Agent to Negotiate His Internet BillAn AI call negotiated a lower price and faster service, but Yang still had to approve the change himself.
 33:09ENPeter Yang· 2026년 11월 1일팟캐스트 · 2명Jaclyn Konzelmann: When AI Can Build More, Choose What Deserves to Exist게스트 Jaclyn Konzelmann · 진행자 Peter YangGoogle Labs pairs short strategy documents with prototypes, user co-creation and lessons from experiments that end.
 13:05ENPeter Yang· 2026년 10월 28일팟캐스트Peter Yang Tests Genie 4: Convincing Worlds, Unfinished GameplayFive live demonstrations show scenes that respond to prompts and sound, alongside inconsistent actions and limited game mechanics.
 1:06ENPeter Yang· 2026년 10월 26일팟캐스트Peter Yang on Setting Up Payroll for a One-Person BusinessIn a paid partnership, Yang describes the paperwork he encountered and a payroll product integrated with a business account.