En 30 secondes
Theo Browne traces the Microsoft–OpenAI relationship from its 2019 investment through the April 2026 amendment and examines OpenAI’s Amazon partnership. He discusses enterprise distribution, his own Azure performance tests, the later improvement he reports, and the role of specialized AI chips.
- 1A revised partnershipMicrosoft remains the primary cloud partner; OpenAI can serve products through other cloud providers under the amended agreement.
- 2Revenue share remains one-wayOpenAI’s payments to Microsoft continue through 2030 subject to a cap; Microsoft no longer pays a revenue share to OpenAI.
- 3Amazon and BedrockThe February 2026 announcement described a stateful runtime and other AWS collaboration under the then-existing terms.
- 4Azure performance and the updateTheo describes intermittent slowdowns and later reports a substantial improvement after Microsoft responded.
- 5Trainium commitmentsOpenAI and AWS announced a large expansion and approximately two gigawatts of Trainium capacity, with future delivery plans.
À retenir
- The April 2026 amendment changed exclusivity but did not end the Microsoft–OpenAI partnership.
- Microsoft’s model and product IP license continues through 2032 on a non-exclusive basis.
- OpenAI’s revenue share to Microsoft continues through 2030 subject to a cap; the reverse payment ended.
- Cloud credits and model eligibility depend on the actual program and contract.
- Performance charts and benchmarks apply to specific models and periods; Theo reported a later Azure improvement.
- Announced compute commitments are plans, not proof that all capacity is already operating.
Lire le texte remanié, chapitre par chapitre
From investment to a changing partnership
Theo introduces the history and distinguishes the amended relationship from an actual termination.
The Microsoft–OpenAI relationship is more interesting than its headlines suggest. Their partnership began in 2019 and has changed substantially. I describe the April 2026 amendment as a breakup, but the companies did not end their partnership: Microsoft remains a major shareholder and primary cloud partner, while exclusivity and revenue-sharing terms changed.
Early Azure exclusivity and AGI
The 2019 investment linked OpenAI research to Microsoft infrastructure. Later agreements treated AGI and IP rights in distinct ways.
OpenAI originally framed its mission around making the benefits of advanced AI widely available. In 2019, Microsoft announced a $1 billion investment and a partnership to develop large-scale AI infrastructure on Azure. The arrangement provided capital and compute for research long before ChatGPT became a mainstream product.
Azure became OpenAI’s exclusive cloud provider under the early agreement, and Microsoft was positioned as a preferred partner for commercializing some pre-AGI technologies. The details of infrastructure hosting, distribution and intellectual-property licensing are different questions; an early cloud exclusivity clause does not by itself describe every later model-access arrangement.
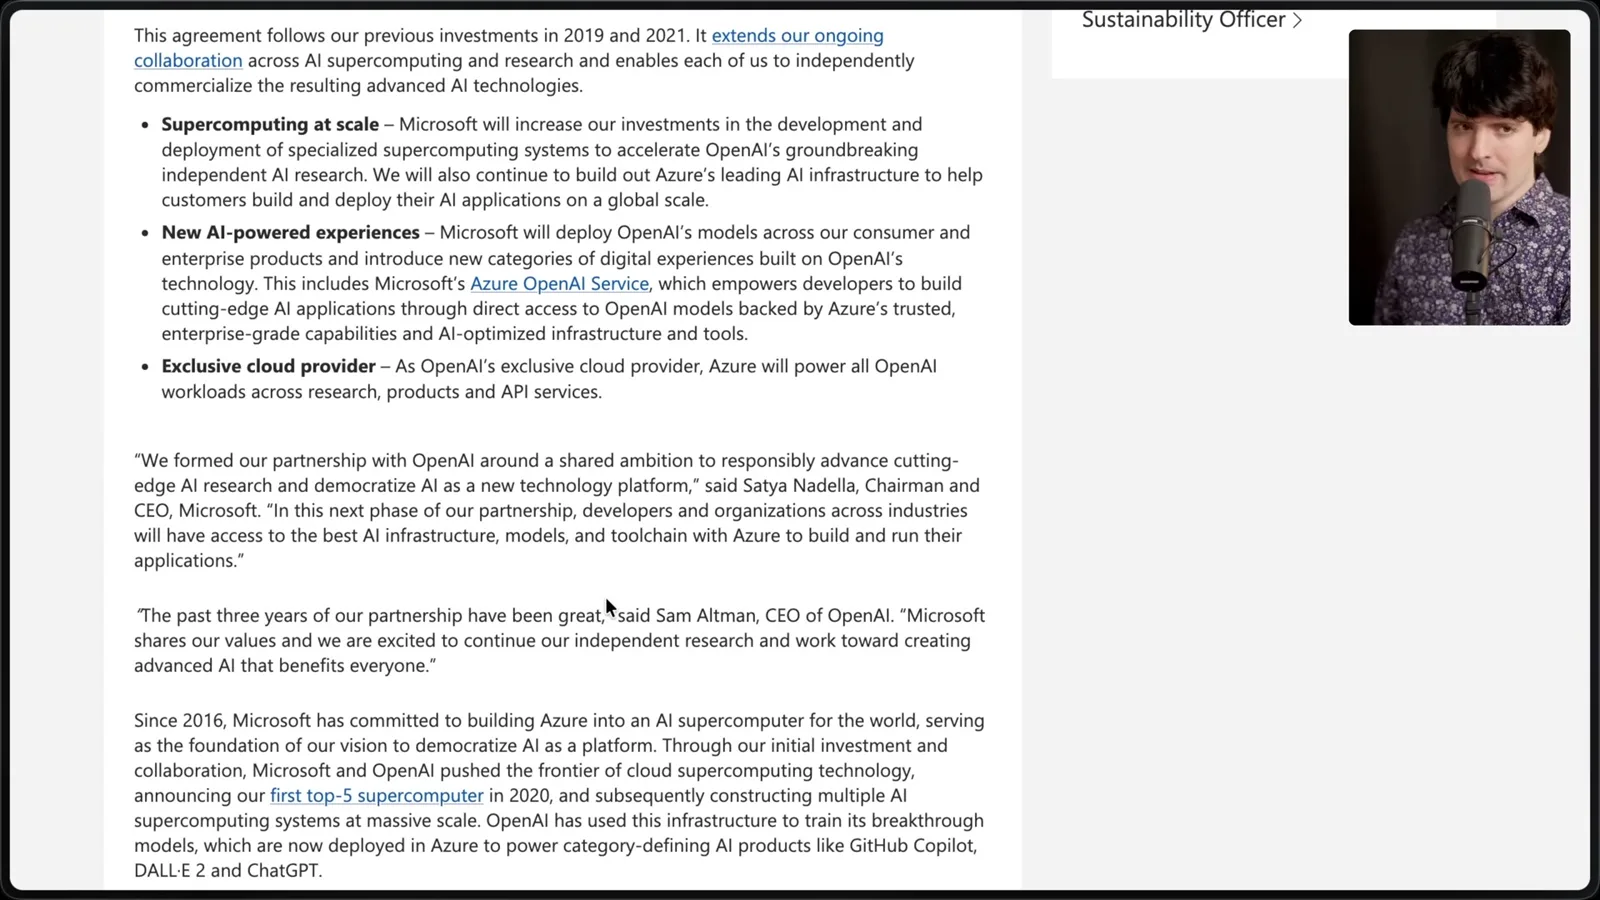
The GPT-2 era helps explain the timing: the technology was interesting to researchers before it was a mass-market product. Microsoft invested before the wave of attention around GPT-3 and ChatGPT. In 2023, it extended the partnership with a multiyear, multibillion-dollar investment following earlier investments in 2019 and 2021.
The early focus on pre-AGI technology created a contractual question: what happens when AGI is declared, and who decides what that means? “AGI” is contested as a technical concept, while contractual definitions and decision procedures can be more specific. The parties’ actual rights depend on the agreements, not a general definition alone.
Reasoning models and reported tensions
Theo revisits o1 and reporting about disagreements over information sharing. He labels private motives and contractual conclusions as uncertain.
In 2024, OpenAI introduced o1, emphasizing additional reasoning before answering. I see it as a major change in model behavior and capabilities, although the video’s benchmark comparisons are historical examples rather than proof of a model’s performance on every task. Later reasoning models and approaches broadened the field.
OpenAI did not expose every part of its reasoning process publicly, and the model was expensive compared with ordinary chat models at the time. I also point to DeepSeek as an important subsequent entrant. Different labs’ research, compute and product decisions affected how quickly they could compete.
I discuss reporting about tension over what research information Microsoft received from OpenAI. Those reports describe disagreements attributed to people familiar with the companies; they do not independently establish every contractual obligation or prove a breach. My description of the episode as the start of a breakup is interpretation.
One report I reference describes Microsoft AI chief Mustafa Suleyman pressing OpenAI staff for more information about o1. I connect that to Microsoft’s interest in developing its own models, but the companies’ internal discussions and motives are not fully public. The account should be read as reported, not as a complete record of the negotiation.
The 2025 agreement
The restructuring announcement differentiated model and product IP from research rights and set out conditions on distribution.
The 2025 restructuring announcement set out a more detailed agreement. It described Microsoft’s investment as approximately 27% of OpenAI Group PBC on an as-converted, diluted basis, with an indicated value of about $135 billion at that time. These are the announcement’s historical valuation figures, not a current market quote.
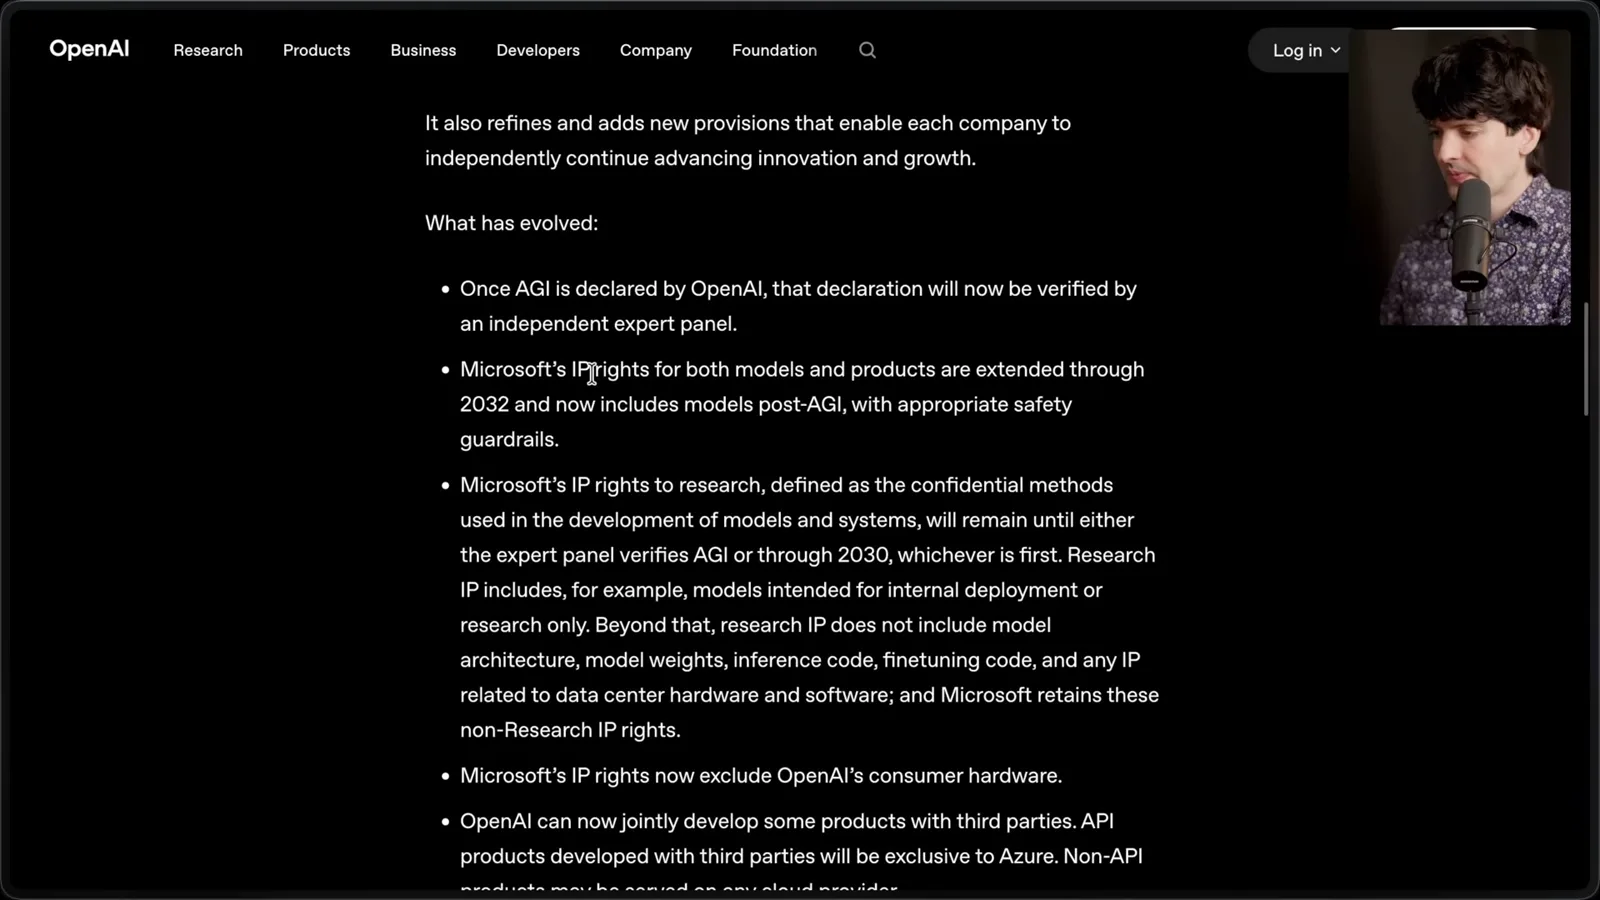
The 2025 terms distinguished model and product IP from confidential research methods. Microsoft’s model and product rights were extended through 2032, including post-AGI models with safety guardrails; the research rights were tied to an expert-panel AGI verification or 2030, whichever came first. The full agreement contains more nuance than a single “all IP” label.
The same announcement described room for third-party products, independent AGI work and some open-weight releases, subject to its conditions. At that stage, API arrangements and non-API products had different cloud provisions. I also speculate about why particular products or partners might have wanted more flexibility; those reasons were not confirmed by the agreement.
I cite reporting that Microsoft leaders were frustrated by the gap between their research and OpenAI’s results. That is context from reported accounts, not a complete explanation for either company’s decisions. Corporate agreements reflect many incentives, including research, investment, distribution and access to infrastructure.
The April 2026 amendment
Microsoft remains the primary cloud partner, while licensing becomes non-exclusive. The two directions of revenue sharing have different outcomes.
On April 27, 2026, OpenAI announced an amended agreement. Microsoft remains its primary cloud partner, and products ship first on Azure unless Microsoft cannot and chooses not to support the necessary capabilities. OpenAI can now serve all its products through any cloud provider. This is a substantial change in flexibility, not the end of the relationship.
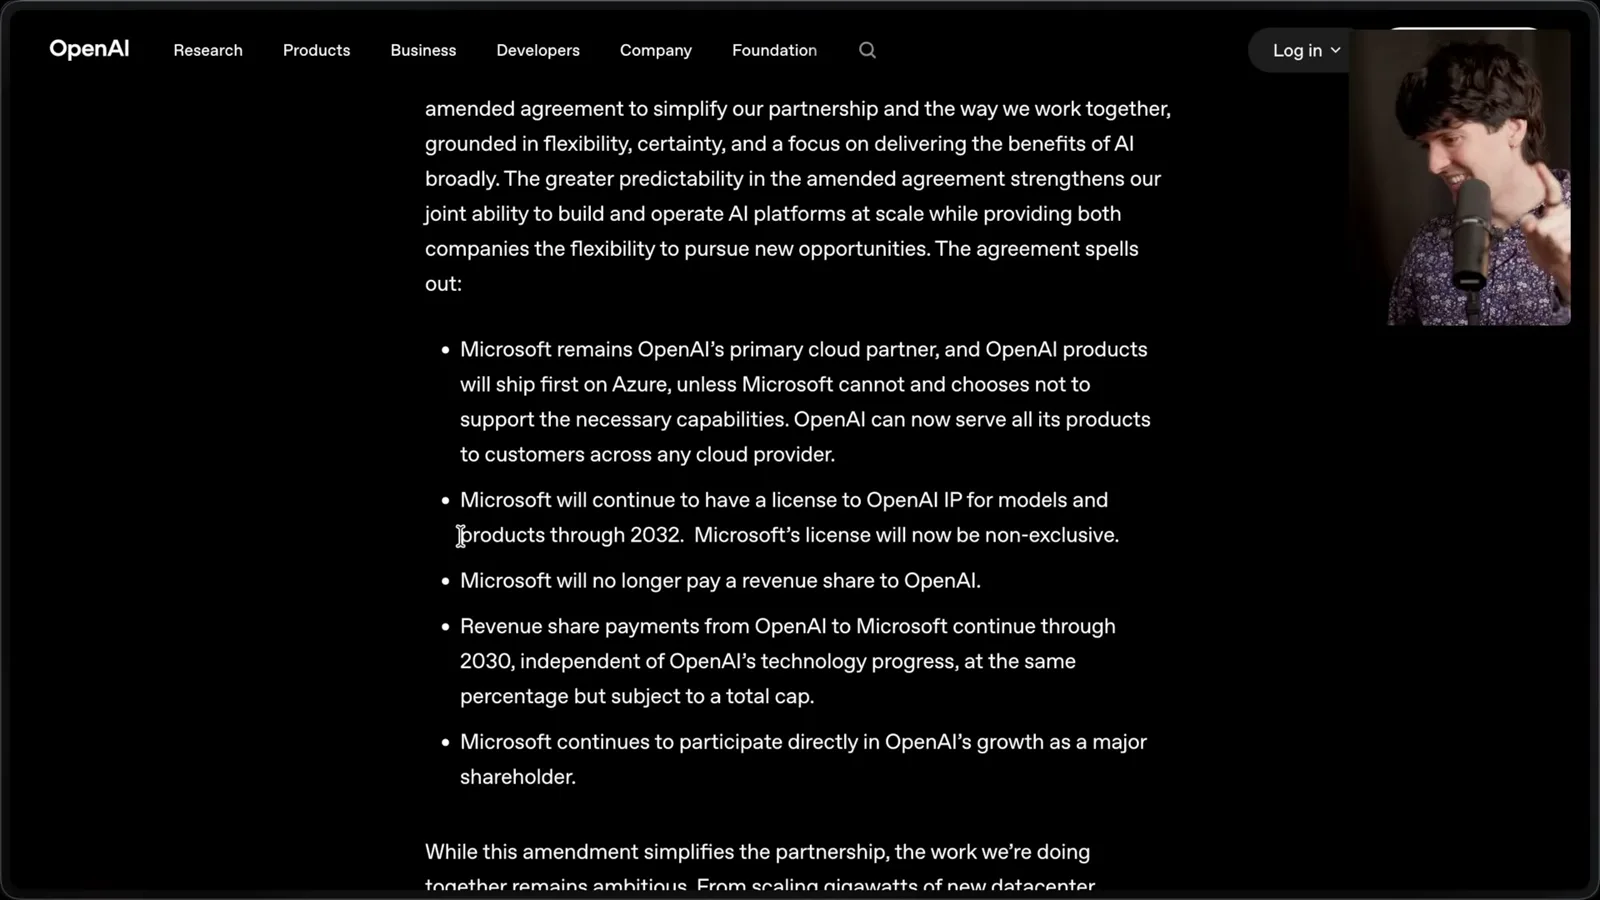
Microsoft retains a license to OpenAI model and product IP through 2032, but that license becomes non-exclusive. The public announcement does not spell out every detailed research-IP condition, so I cannot infer from this summary exactly which confidential-method rights changed.
The revenue-share directions matter. Microsoft will no longer pay OpenAI a revenue share, while OpenAI’s revenue-share payments to Microsoft continue through 2030 at the same percentage, subject to a total cap and independent of technological progress. In the video I wondered whether this had become a profit share; the published announcement says revenue share, so that speculation should not be taken as fact.
Amazon, enterprise access and cloud credits
Theo discusses the Bedrock partnership, cloud distribution and the limits of generalizing from his own credit arrangements.
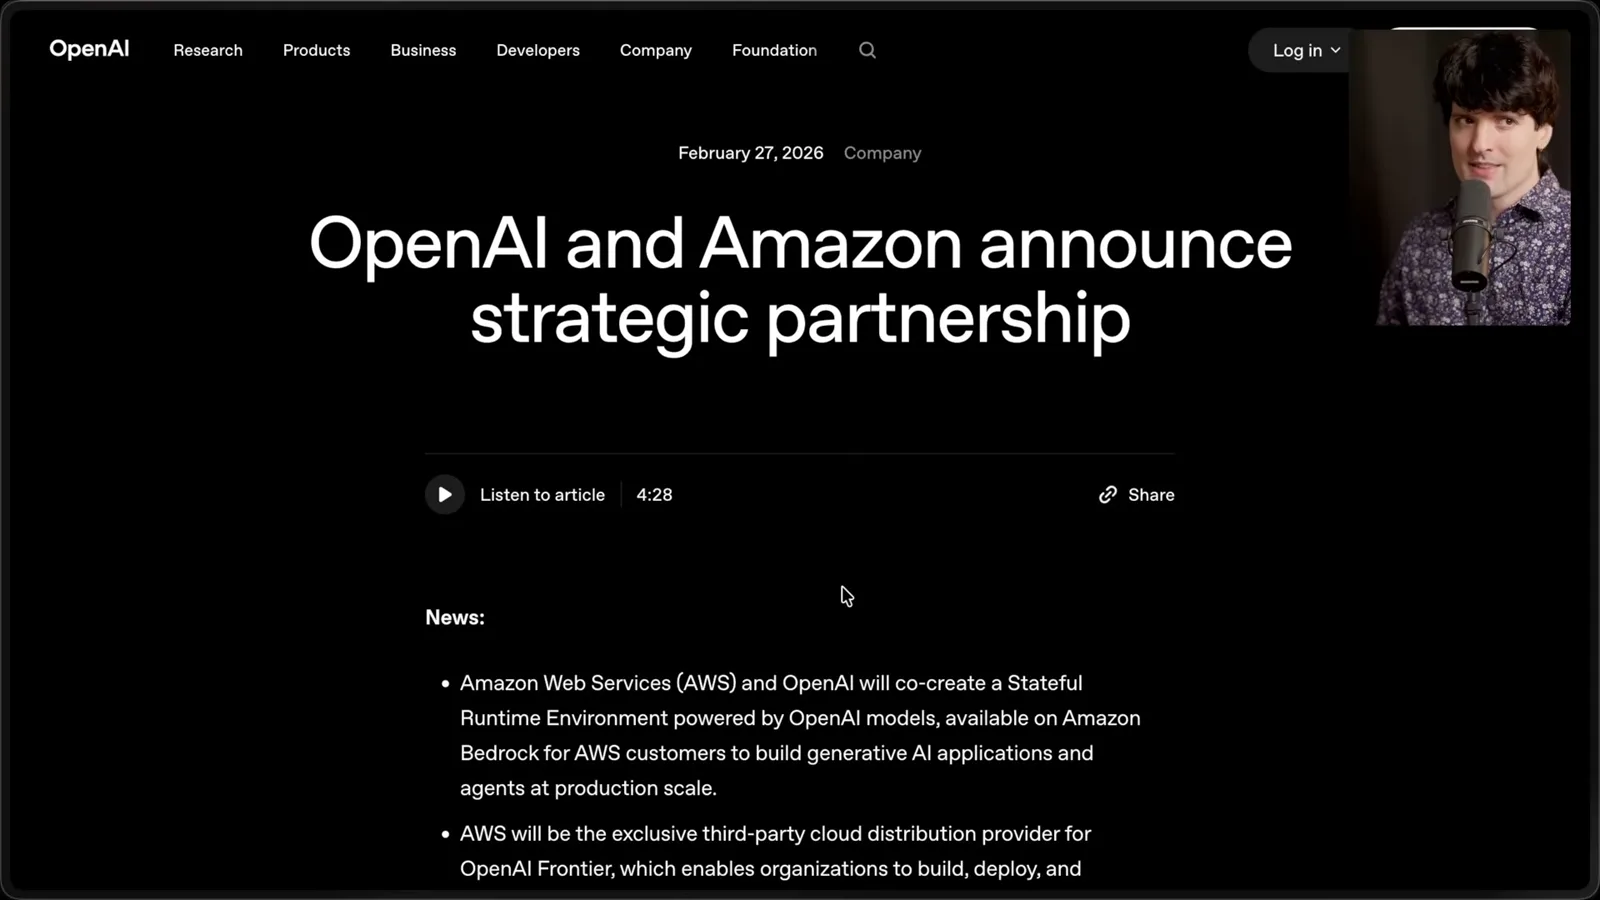
OpenAI and Amazon had separately announced a strategic partnership in February 2026. Their plans included a stateful runtime for AWS customers through Amazon Bedrock, third-party distribution of OpenAI Frontier, and Amazon investment. The February Microsoft–OpenAI statement said the Amazon collaboration was compatible with the agreement then in force, including its Azure rules for stateless APIs.
A stateful runtime can preserve context across interactions, which may help applications and agents avoid repeatedly rebuilding state. Caching and data locality can also matter. I prefer AWS for this type of work, but the claim that Azure could not implement it is my opinion, not a technical proof.
The Amazon announcement also described approximately two gigawatts of Trainium capacity and a $50 billion investment commitment. These are announced plans and commitments, not proof that all capacity was already operating. The amended Microsoft terms later broadened OpenAI’s cloud-distribution flexibility.
I argue that enterprise distribution helps explain OpenAI’s interest in AWS: many organizations already use Bedrock and may prefer to obtain models through an existing cloud account. A reported internal memo described strong customer interest. My further claim that Anthropic’s growth was the decisive cause of the amendment is speculation about private strategy.
Cloud credits can influence a startup’s economics. I describe offers from several providers and disclose that my own company received $1 million in Azure credits, while spending substantial amounts on model inference. Those are my circumstances, not standard terms that every startup can obtain.
I say that the credits available to me did not cover Anthropic models in the arrangements I tried, while other model workloads were eligible. Credit eligibility varies by program, contract, product and time; my experience does not prove a blanket restriction across every cloud or customer.
I speculate that revenue-sharing obligations might explain why providers would not discount those requests for me. My example of a 50% share and a $1 million credit is hypothetical. I do not know the actual private agreements, and other contractual or commercial explanations are possible.
From my experience, enterprises often want to use models within their existing cloud environment. Anthropic’s availability across multiple clouds can therefore be valuable, and broader OpenAI availability could give those customers another choice. Whether a given model, region or credit is available still depends on the service’s current terms.
Azure benchmark and subsequent improvement
Theo describes disappointing historical measurements and then reports improvements after Microsoft responded.
I explain why I had not used the Azure credit for the inference workload I wanted: I observed severe, intermittent output-speed drops compared with OpenAI’s direct endpoint. I show Artificial Analysis charts and describe earlier tests. Those observations concern particular models, measurements and periods, not all Azure services or all workloads.
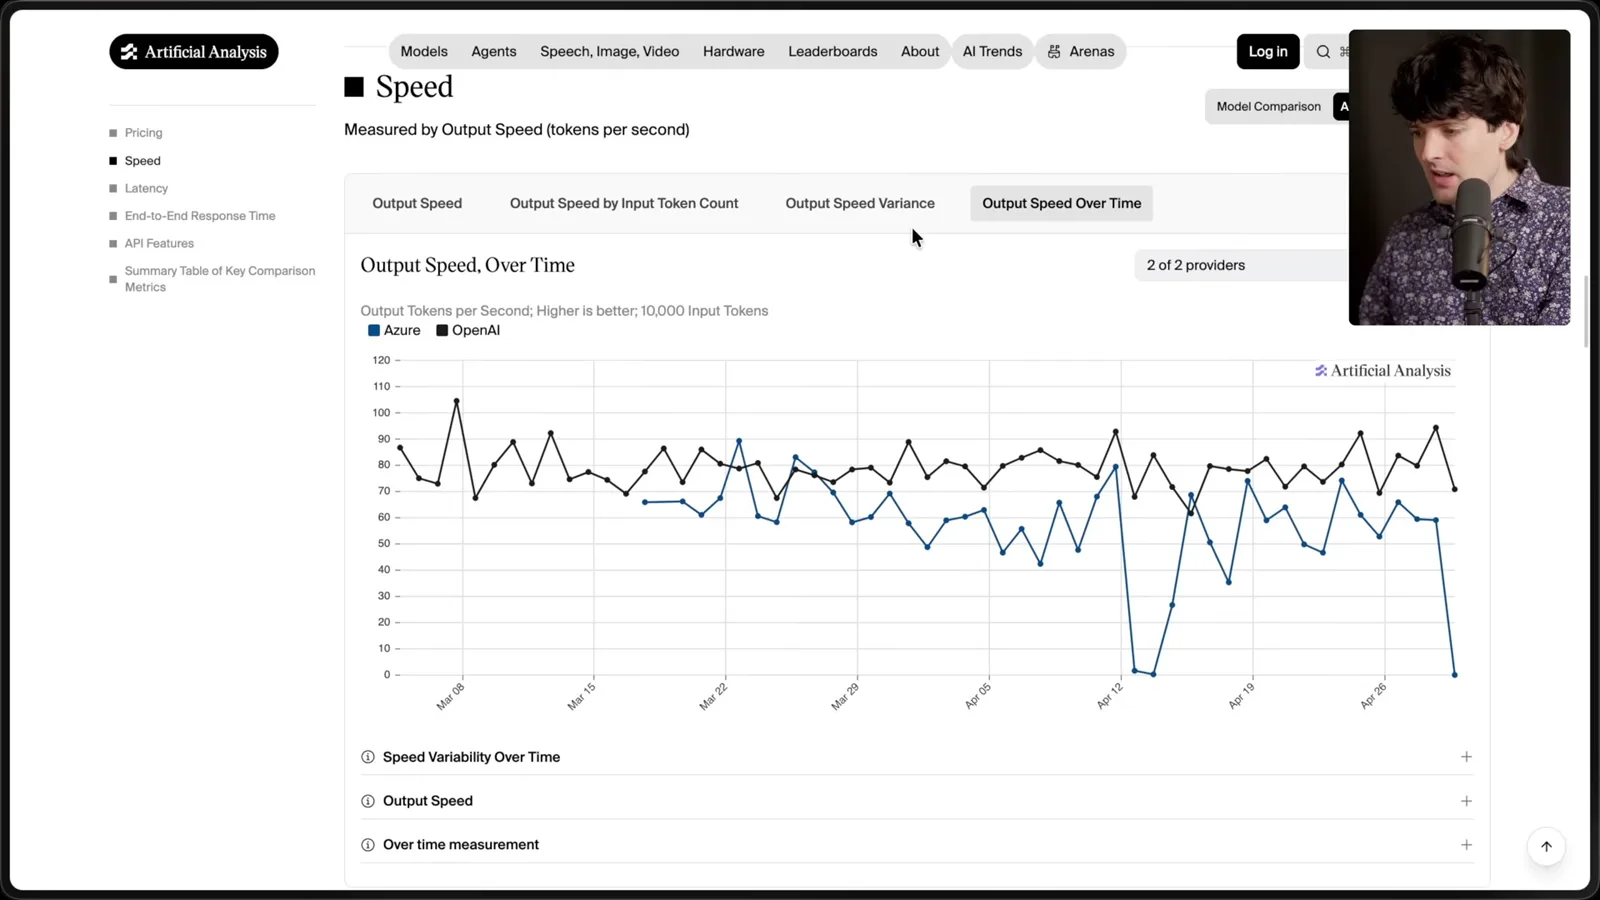
I had raised the issue with Microsoft for over a year and describe meetings with its infrastructure team. My frustration led me to recommend avoiding Azure for this use case in the original recording. That recommendation was based on my experience at that time, and the later update in the same video changes the picture.
In the update, I built Azure Bench to measure the discrepancy and reported an average 2.2-times slowdown and a 15-times difference at the reported worst decile for a tested configuration. These are my benchmark results under its conditions, not independent guarantees about every deployment.
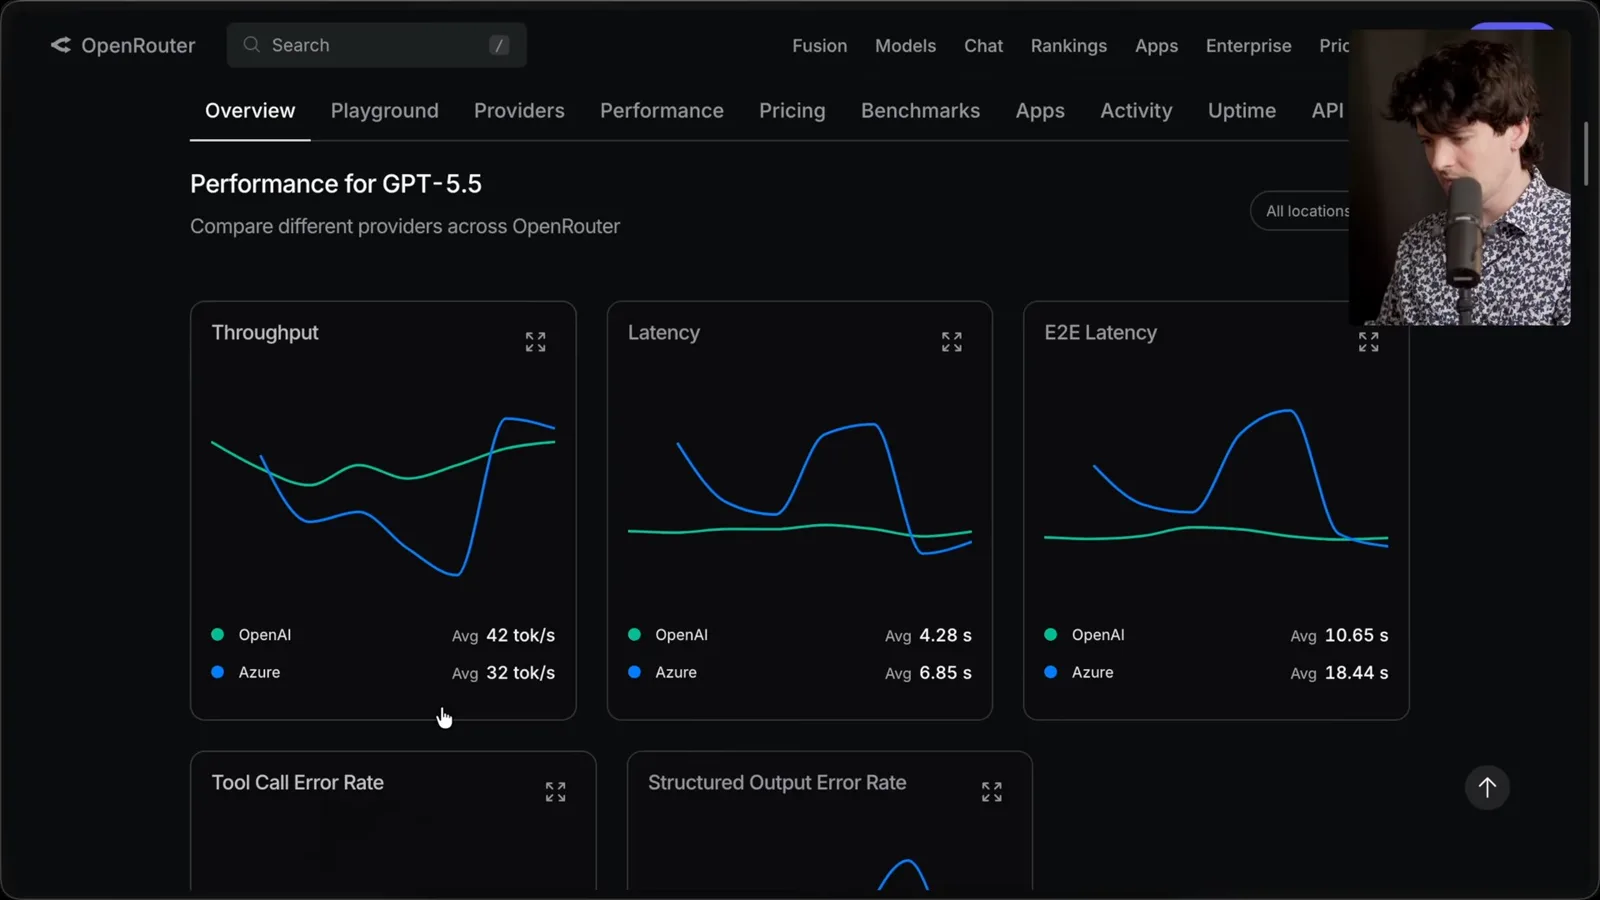
I say Microsoft responded and the measured performance improved by the next day. OpenRouter charts I show also suggest throughput and latency improved during that period. I credit the team for responding; a snapshot after a fix is encouraging but does not establish future performance in every region or model.
Trainium and the infrastructure race
The AWS commitment adds specialized accelerators to the discussion. Future performance and deliveries remain to be evaluated.
The AWS announcement raises another question: how well will OpenAI workloads run on Trainium? Supporting a different accelerator requires engineering work, and I am curious about the outcome. My suggestion that hardware changes may affect another company’s model quality is speculative; the video provides no controlled evidence of that causation.
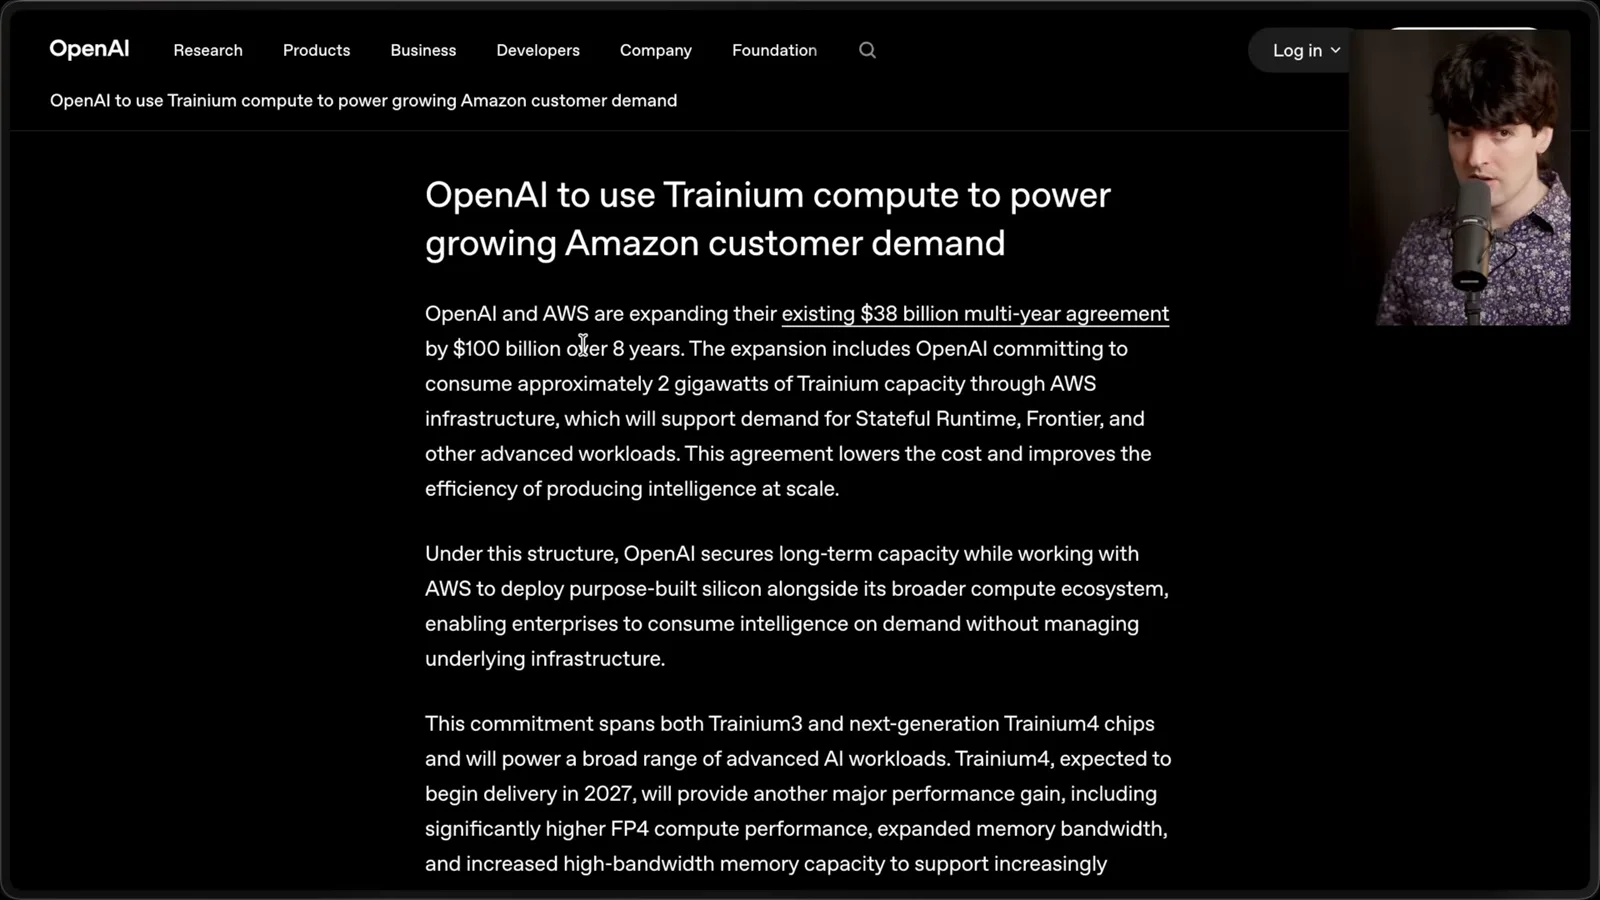
OpenAI and AWS announced an expansion of an existing $38 billion multiyear agreement by $100 billion over eight years, including approximately two gigawatts of Trainium capacity. The announcement described Trainium 3 and a planned Trainium 4 generation, with delivery expected from 2027. These are commitments and expectations, not completed deliveries.
I expect competition among model providers to be accompanied by competition among accelerator and cloud platforms. Whether NVIDIA, AMD, AWS Trainium or Google’s TPUs gain ground is uncertain. The practical lesson for builders is to measure performance, availability, contract terms and portability for the actual workload rather than assume a permanent winner.
Sur la même chaîne
 38:47EN
 Theo - t3․gg· 28 oct. 2026Theo’s Long-Running Agent Experiments: Verification, Compute and CostTheo Browne · Ping LabsA skateboard game and two compiler projects show how repeated checks and flexible compute can sustain agent work—and how expensive those loops can become.
 36:07ENTheo - t3․gg· 27 oct. 2026Theo on Token Costs, Coding Agents, and the Price of AI CapabilityTheo Browne · Ping LabsA viral estimate of Lauren's AI spending prompts a closer look at cache pricing, benchmarks, and the changing work of coding agents.
 30:37ENTheo - t3․gg· 26 oct. 2026Theo’s Three Skills for Reviewing and Shipping with Coding AgentsTheo Browne · Ping LabsHow sol-loop, full-send and full-stop encode review, verification and different levels of merge authority.
 0:43ENTheo - t3․gg· 23 oct. 2026Theo Distinguishes Security Vulnerabilities from Active AttacksTheo Browne · Ping LabsA short explanation of why disclosed software flaws and reported attacks are different kinds of security news.
 29:22ENTheo - t3․gg· 22 oct. 2026Theo on Security Vulnerabilities, Stolen API Keys and AITheo Browne · Ping LabsA look at the gap between vulnerability disclosure and patching, and a speculative account of why stolen inference keys may be valuable.
 31:13ENTheo - t3․gg· 20 oct. 2026Theo on Why Smarter Models Help More Than DevelopersTheo Browne · Ping LabsFrom game modifications to compiler experiments, Theo revisits his assumptions about who benefits from more capable AI.